{{item.videoDuration}}
{{item.title}}
{{item.text}}

{{item.videoDuration}}
{{item.text}}
THE THESIS. The value gap in M&A opens when leaders leave the operating implications of the deal thesis unresolved. Successful acquirers identify the few decisions that matter most, make them early, and connect them to accountable value initiatives and proof.
M&A is entering a period of greater concentration and greater consequence. Deal volume is flat to down, geopolitical, economic, and interest rate uncertainty remain high, and aggregate deal value has reached record levels. The companies still committing capital are often well-capitalized businesses making larger bets on growth, margin expansion, capabilities, technology, and strategic position.
The integration implication is direct. A large transaction cannot be managed as a traditional post-close exercise focused on connecting systems, completing Day One tasks, and stabilizing the organization. Those activities remain necessary; however, they are no longer sufficient. The integration plan must drive the operating decisions that turn the deal's strategic promise into the way the combined company competes and performs.
This conclusion comes from PwC's 2026 M&A Integration Survey, which captures the experience of executives involved in a merger or acquisition transaction during the past three years at organizations with annual revenue of $1 billion or more. We studied what these executives said about their deal objectives, the timing of their decisions, the value initiatives they built, and the confidence they had in the results.
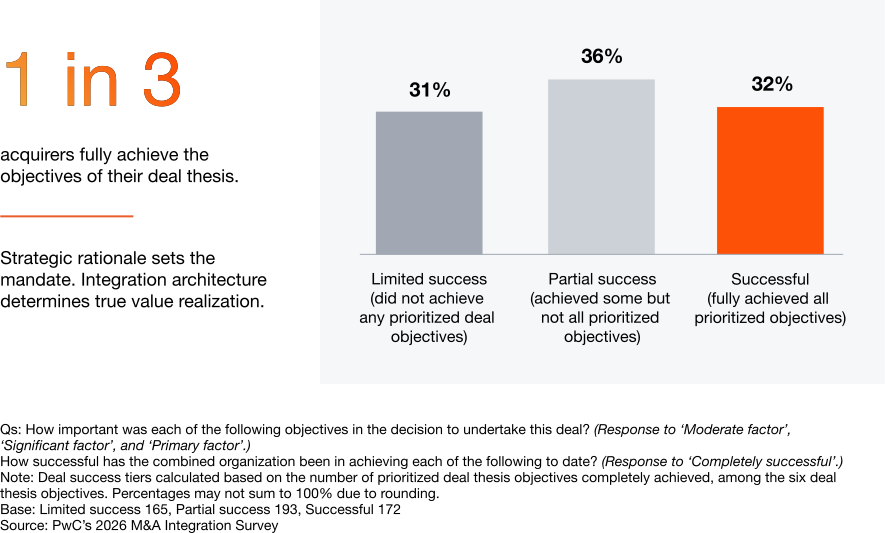
Our primary observations are anchored in one foundational finding: only about one in three acquirers fully achieved all their prioritized deal thesis objectives. The survey findings do not suggest that the other two-thirds lacked strategic ambition or chose the wrong deal themes. Instead, it shows where the performance gap opens: in the decisions that translate the thesis into the combined company's customers, products, capabilities, organization, and measures of value. That distance—between the deal thesis and the choices required to execute it—is the decision gap.
THE DECISION GAP is the distance between the deal thesis and the explicit, owned choices required to make that thesis real. It appears when critical choices are made too late, remain unresolved or implicit, or never translate into funded actions and measurable value commitments.
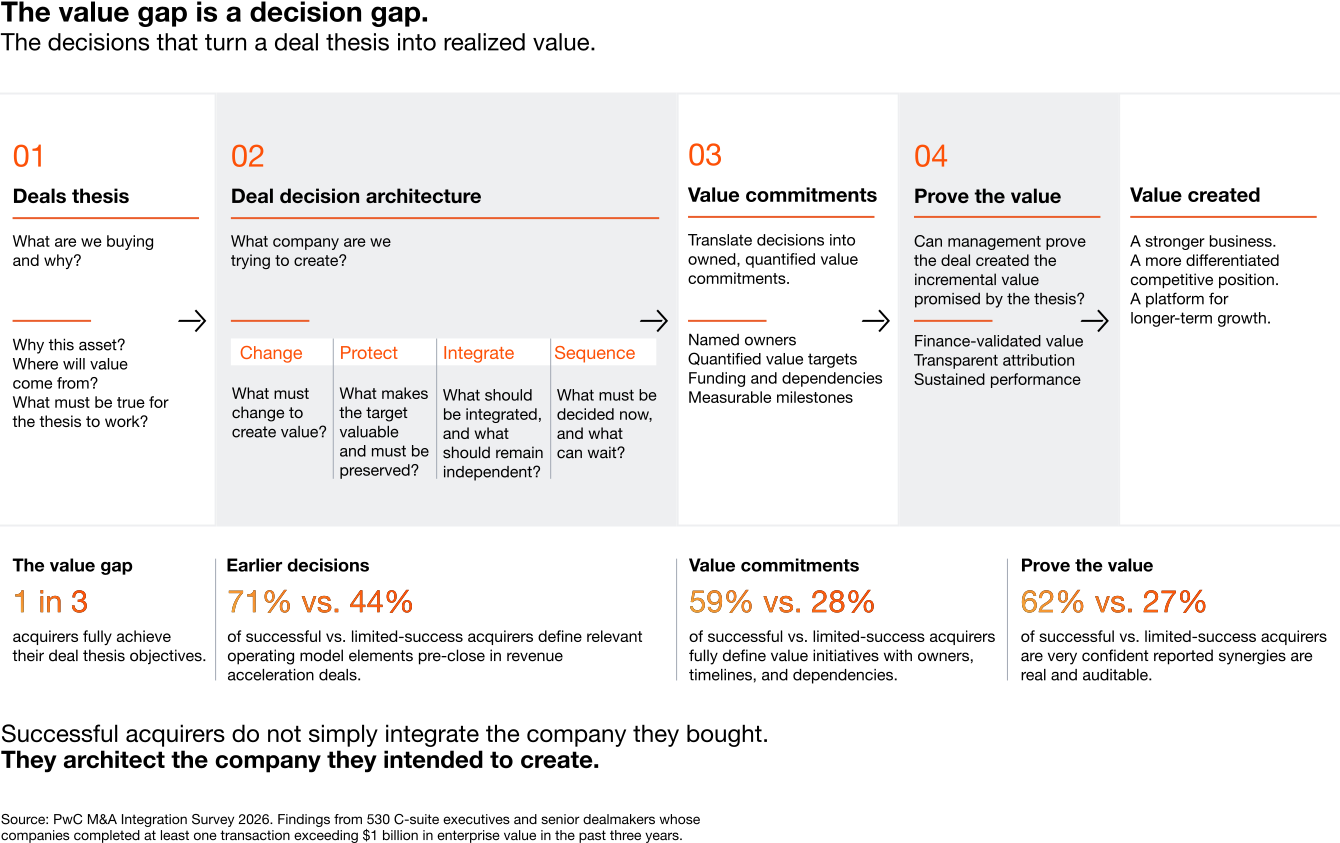
The finding is important because integration is often treated as a period of execution after the deal has been designed. The highest-performing acquirers treat it differently. Before Day One, they decide what must change, what must be protected, what should be integrated, and what should be sequenced over time—effectively defining the combined entity’s target operating model to deliver the value the deal was intended to create. Too often acquirers jump from deal thesis to integration plan and treat the target operating model as something that emerges during execution. That skipped step is where the value leaks. It is the small set of choices that decide how the combined company will run to deliver the thesis and protect what made the target worth buying.
THE CEO QUESTION. What are the three or four changes this deal requires, and which decisions become harder and more expensive if we defer them past Day One?
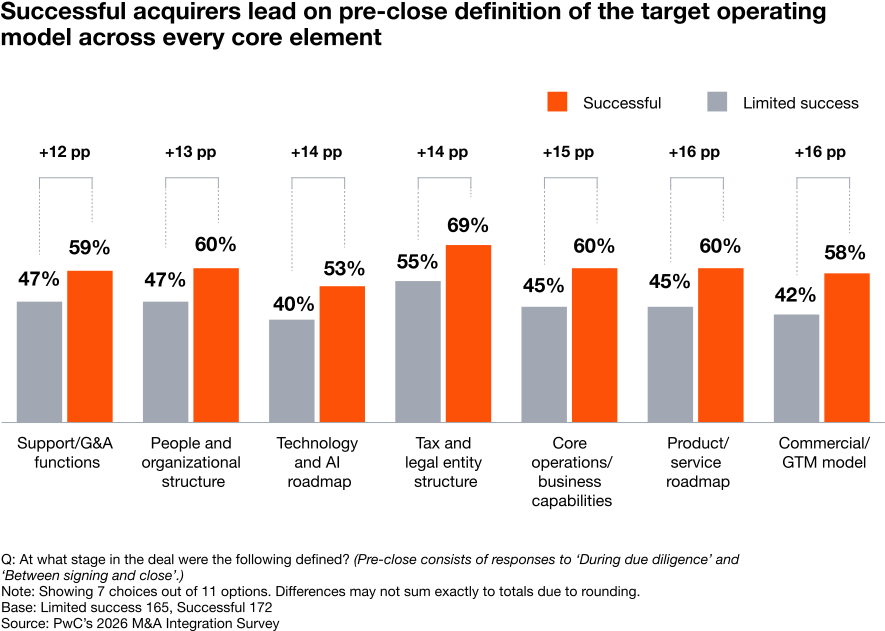
The historical comparisons make the current finding harder to dismiss as a short-term fluctuation. In 2020, 59% of acquirers reported having a target operating model in place at signing; by 2023, that figure had moved only two percentage points, to 61%. Meanwhile, the 2026 survey shows successful acquirers leading limited-success acquirers by 13 to 27 percentage points in the pre-close definition of core elements. The market has plenty of frameworks but has struggled to move the few decisions that matter upstream.
The same tension appears in the people data. Seven in ten acquirers named talent as a top deal objective in 2017, yet only 16% of respondents in the current survey reported assessing leadership and talent pre-sign or conducting people and organizational diligence. Leaders say talent matters; however, we observed that decisions around talent selection, leadership, and organizational design do not always receive the same attention as technology, finance, and commercial strategy.
The familiar explanation. Deals miss their targets because the thesis was too optimistic, the integration was poorly managed, or the organization resisted change. Each explanation has merit. None explains the most actionable pattern in the data.
The survey's answer. The performance gap begins earlier, when leaders decide whether the thesis will shape how the combined company actually operates.
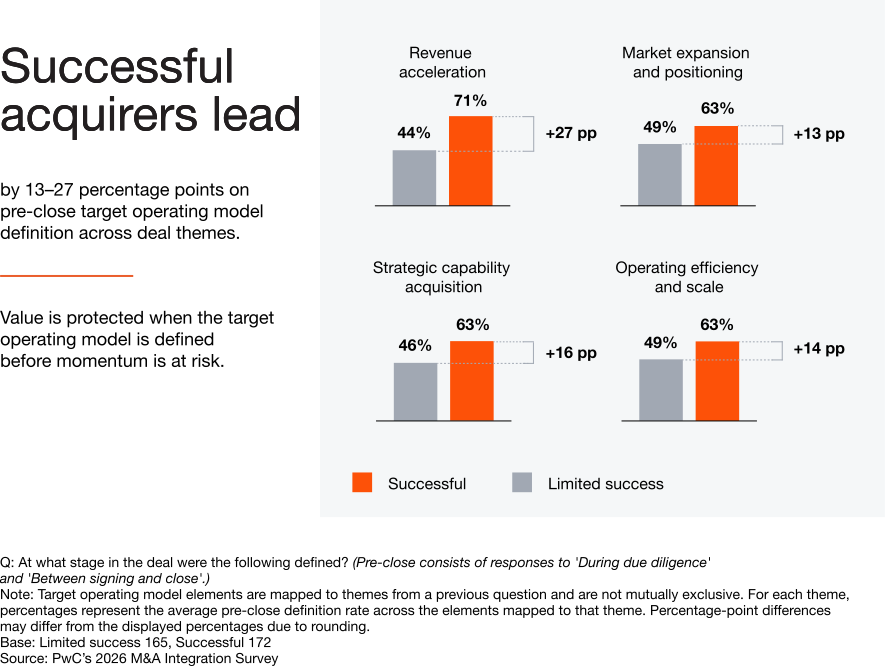
The survey findings suggest that successful and less successful acquirers have historically justified deals using the following value creation themes: market expansion, strategic capability acquisition, operating efficiency, or revenue acceleration. However, a gap in success appears when these themes are not translated into a plan that resolves the few choices that determine the value case.
But successful acquirers were more likely to define thesis-relevant operating-model elements before close across every deal theme. The sharpest gap appears in revenue-acceleration transactions: 71% of successful acquirers defined the relevant elements pre-close, compared with 44% of limited-success acquirers. That 27-point difference is not an abstract design issue. It is the difference between entering Day One with decisions on customer ownership, pricing, distribution, incentives, and product priorities, or asking two commercial organizations to resolve those choices while the market keeps moving.
THE ATTENTION POINT. Revenue synergies are often the most visible promise in the deal model and the least forgiving source of value when commercial decisions wait until after close.
The term Target Operating Model can imply a comprehensive future-state exercise. That is not the argument here. Every acquisition does not require a wholesale rewrite of the buyer's operating model. Every acquisition does, however, require a deliberate answer to what the combination must change to deliver the thesis.
For one deal, the answer may be to combine two sales forces. For another, it may be to preserve the target's product and engineering model while integrating finance, data governance, and selected infrastructure. Leadership should determine, and make, the three or four choices that protect growth, preserve the capability acquired, and put accountability where value will be created.
This is the practical meaning of operating model decisions in an integration strategy and plan. The choices are specific to the thesis; the project plan is the mechanism for executing them after they are made.
Take the example of a large Consumer Packaged Goods company acquiring an adjacent product line in a hot, emerging category. Translating the deal thesis into key decisions is how you can bridge the gap from strategy to execution. This could include:
Highly effective dealmakers make these design decisions early and communicate them broadly so there is focus. Further, the integration work can concentrate on only those activities that bring the deal thesis to life.
The decision set can be made more concrete by separating four actions: change what creates the intended synergy, protect what made the target valuable, integrate the capabilities and operations that should come together, and sequence what needs more evidence. Sequencing requires judgment about which decisions become expensive to reverse, which depend on evidence that only emerges after close, and where delay preserves optionality rather than destroying value. That framework keeps the integration from treating every unresolved issue as equally urgent.
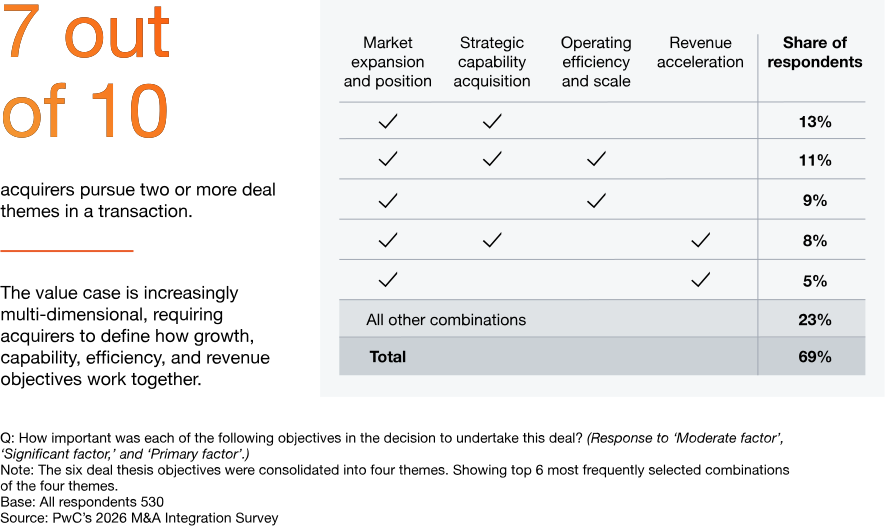
Most deals carry more than one value objective. Respondents selected roughly two primary deal themes per transaction, most often market expansion and strategic capability acquisition. That matters because a single integration template cannot tell leaders what to prioritize. The thesis has to determine the architecture.
A market-expansion deal is not an efficiency deal with a geographic label. A capability acquisition is not a standard functional integration. Each carries a different success model, and each requires a different early decision set.
Deal thesis |
Typically decided before Day One |
Protect or change |
| Market expansion and position | Go-to-market model, distribution, localize products, and organize the product roadmap | Protect customer access; change coverage and channel choices that limit growth |
| Strategic capability acquisition | Product roadmap, branding, critical talent, technology boundaries | Protect the capability that justified the deal; integrate only what improves scale |
| Revenue acceleration | Customer ownership, pricing, incentives, product/feature bundling and cross sell, and salesforce design | Protect customer momentum; change the commercial system that blocks cross-sell |
| Operating efficiency and scale | Sources of efficiency whether, process, function, system, vendor management and the new organization that will own the work | Change duplicated infrastructure; protect the capabilities that sustain service |
A delayed decision is not simply a decision made later. It can mean lost customers, lost talent, duplicated investment, slower synergy capture, and a period in which the combined company operates below the performance of either legacy business. Momentum may return; the value lost during the delay does not.
A value driver is not yet value. It is a hypothesis that becomes more credible when leaders turn it into an initiative with an owner, a timeline, dependencies, funding, and a measure that finance can validate. Identifying synergy opportunities is more than an analytical exercise. It is a management commitment: a choice about how the company will operate, who will be accountable, what resources will be provided, and how the result will be judged.
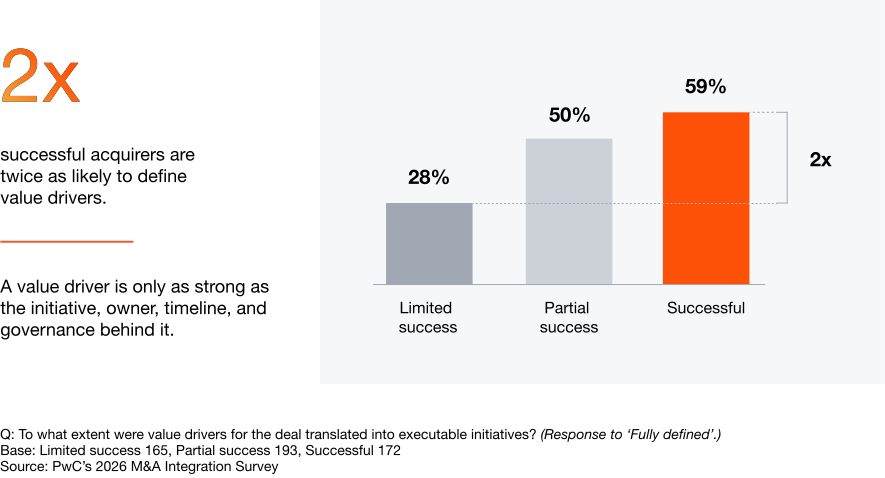
Only 46% of all respondents said value drivers were fully translated into executable initiatives with clear owners, timelines, and dependencies before integration. The figure rises to 59% among successful acquirers and falls to 28% among limited-success acquirers. The 31-point gap is the clearest evidence in the survey findings that value creation depends less on the quality of the original synergy case and more on the execution system used to realize it.
A serious value governance system connects the deal thesis to a short list of value priorities and then connects each priority to a named owner with funding, authority, and a method for proving the result. The integration management office is only part of that system; the CEO and executive team still own the choices and the trade-offs.
Governance question |
Minimum decision before Day One |
| What is the value priority? | Name the two or three outcomes that matter most and resolve how they interact. |
| Who is accountable? | Name an executive sponsor and an initiative owner with authority, funding, and escalation rights. |
| What has to happen first? | Document dependencies, milestones, decisions, and the conditions that could stop delivery. |
| How will value be proven? | Set baselines, controls, validation rules, and a reporting cadence that separates realized value from forecast and normal performance. |
| How will incentives work? | Tie incentives to validated outcomes, not simply to reported activity or untested forecasts. |
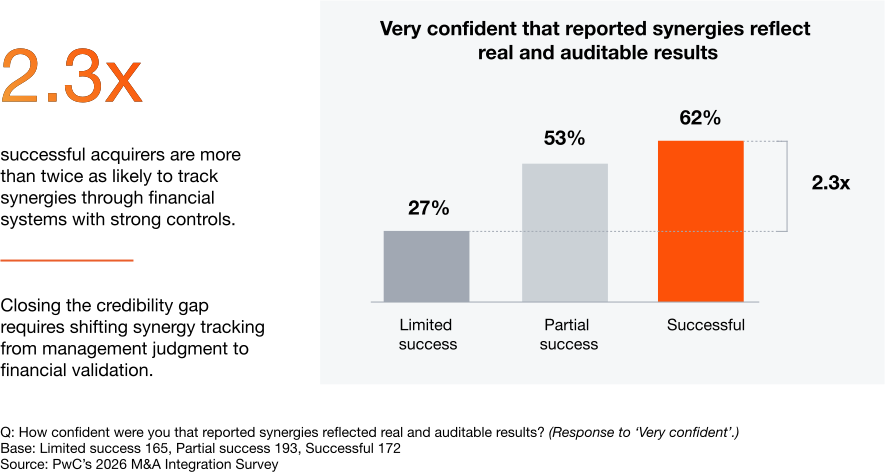
Measurement is the second half of that system. Three in four respondents tie direct and material incentives to synergy outcomes, but fewer than half are very confident that reported synergies reflect real, auditable value. Among successful acquirers, 62% reach that standard, compared with 27% among limited-success acquirers. Incentives should reinforce validated outcomes; they cannot substitute for validation.
That confidence gap matters to the CEO, CFO, board, and investors. A finance-validated value system allows leaders to distinguish realized value from forecasted value, double counting, accounting treatment, and ordinary business performance. It also lets management adjust the integration while there is still time to protect the thesis. A strong measurement capability allows visibility that can credibly create an incentive structure tied directly to the right outcomes.
But the incentive structure is only as strong as the evidence behind it. Proving value means more than reporting that an initiative is complete. Leaders should be able to show what changed, against what baseline, who owns the result, when the value reached the income statement or cash flow, and what evidence supports attribution to the deal. Without that standard, the organization can be rewarded for moving a number without demonstrating that the deal created incremental value.
THE BOARDROOM ISSUE. The question is whether the board can distinguish realized value from forecasted value, double counting, and ordinary business performance.
The strongest governance model therefore connects the deal thesis, the initiative portfolio, the operating decisions, the financial baseline, and the incentive design. It gives the CEO and CFO a common view of where value is captured, where it is at risk, and which unresolved decision requires escalation.
Talent, technology and AI, tax, and regulatory strategy are examples of the enablers that become material when the deal thesis depends on them. The survey findings show that their effect is greatest when leaders move the relevant decisions upstream rather than treating them as specialist workstreams after close.
These four enablers are included because they repeatedly determine whether the thesis can be executed at the promised speed, economics, and level of confidence. They are not necessarily universal pillars of integration. They are also not a complete list; commercial ownership, supply chain, customer experience, and other capabilities belong in the architecture whenever the deal depends on them.
The people question is not only how much to invest in talent. It is which leaders, roles, capabilities, and behaviors the deal depends on, who should lead them, and what must be protected before the organization begins to select, retain, or move people.
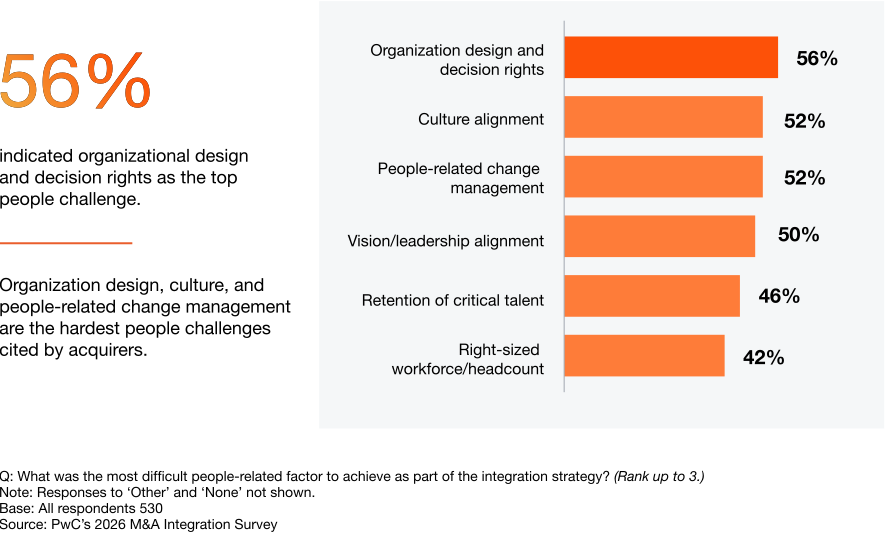
The survey results identify clear organization design and decision rights as the leading people-related challenge, cited by 56% of respondents. Culture alignment and management of people-related change each follow at 52%. These are operating model choices that determine who makes decisions, how leaders work together, and whether the organization understands what the combined company is trying to become.
Acquirers that fully translated the deal thesis into leadership, talent, and organizational actions reported complete success on revenue synergy outcomes at a higher rate than those that did not: 55% versus 34% across the full sample. Among successful deal cohorts, the difference was 62% versus 29%. The survey is self-reported and does not establish causation, but the pattern is strong enough to support a practical conclusion: talent strategy needs the same purposeful discipline as other operating strategy decisions.
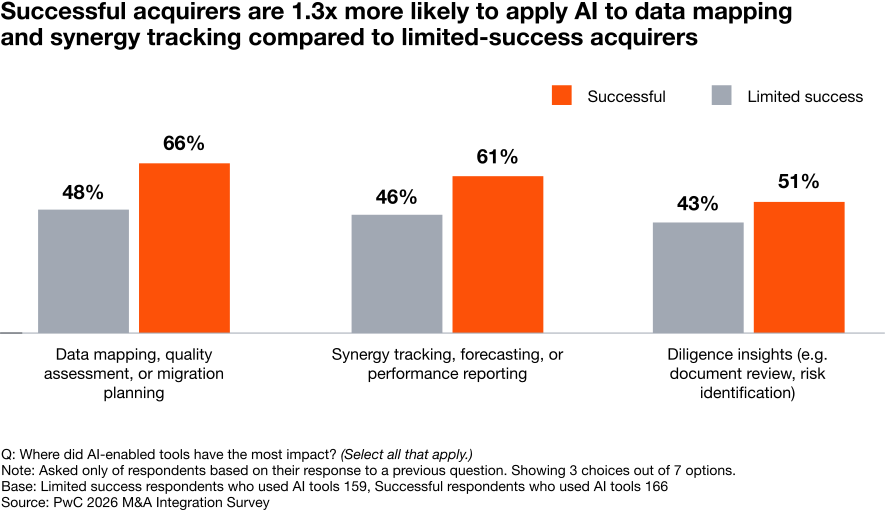
Leaders need to assess where systems, data, and technology will accelerate or constrain the path to full-potential value. That assessment should guide which platforms will support the combined company, how data will be owned and governed, and which architecture choices matter most for customer experience, resilience, cost, and speed. The deal thesis should determine what needs to be integrated or protected early, and what can be sequenced, left separate, or deferred until later stages of the integration.
Technology and data enabled at least a quarter of synergies for nearly nine in ten acquirers, and more than half of synergies for almost a third. Access to new technologies was an important transaction objective for 78% of respondents, up from 72% in PwC's 2023 M&A Integration Survey; among successful acquirers, the latest figure rises to 84%. These findings reinforce that systems, data, and technology are part of the value architecture of the deal: they can enable the thesis, constrain it, or materially change the speed and economics of value capture. The choices should therefore be designed around the value case, including what must be integrated, protected, or left separate.
Within that broader technology and data architecture, leaders also need to be explicit about the role AI is expected to play in the value case. Depending on the deal, AI and broader technology can play a variety of roles from accelerating integration, or unlocking new opportunities, and each scenario calls for a different decision.
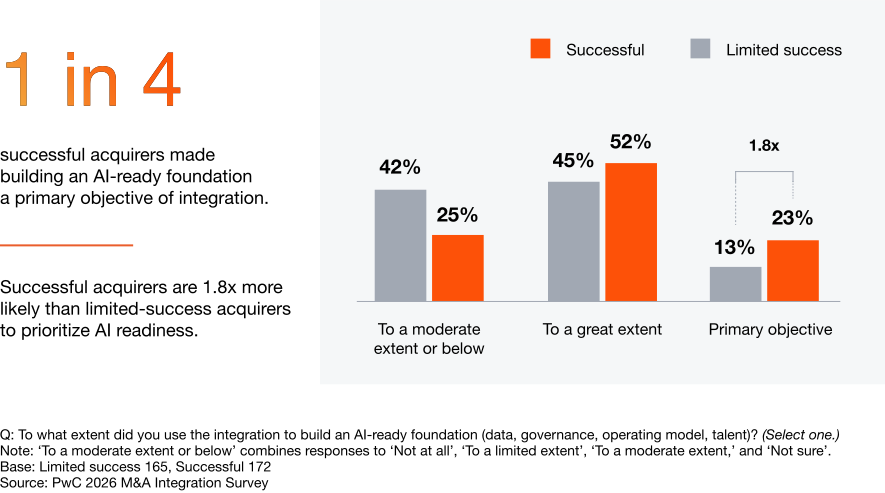
The survey results support the need for this distinction. Roughly three in four acquirers use AI somewhere in integration, but only one in five made building an AI-ready foundation a primary integration objective. Among successful acquirers, that rises to roughly one in four; among limited-success acquirers, it is closer to one in eight. The implication is not that every deal requires an AI transformation. It is that leaders need to determine explicitly where AI contributes to the value thesis and build the data, technology, governance, and talent foundation accordingly. The finding does not mean AI is automatically the next source of value in every deal. It means the value question needs to be explicit rather than collapsed into a generic claim about adoption.
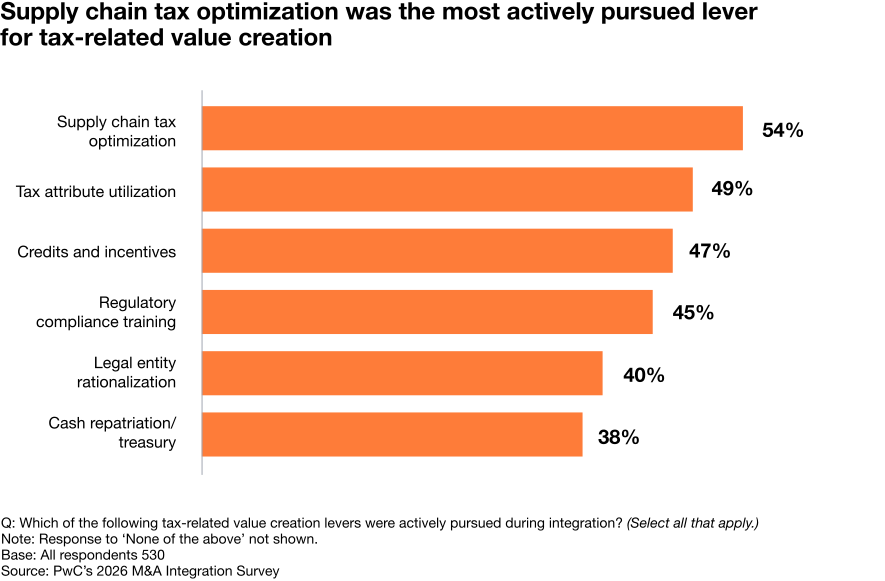
Tax value is broader than post-close operating-model design. Before close, tax diligence can identify inherited risks and acquisition structuring can help preserve or maximize tax attributes. After close, legal-entity structure, supply chain design, transfer pricing, IP ownership, incentives, indirect taxes, and ongoing compliance shape the economics of the combined company.
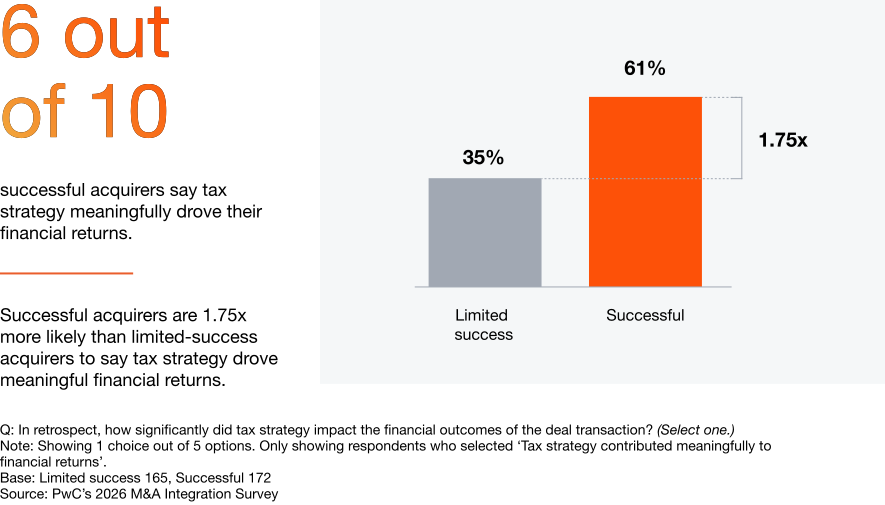
Successful acquirers were more likely to report that tax strategy meaningfully contributed to financial returns: 61% versus 35% among limited-success acquirers. These findings illustrate that tax needs to be in the room when structural choices are made, and the work cannot be treated as complete when the transaction closes.
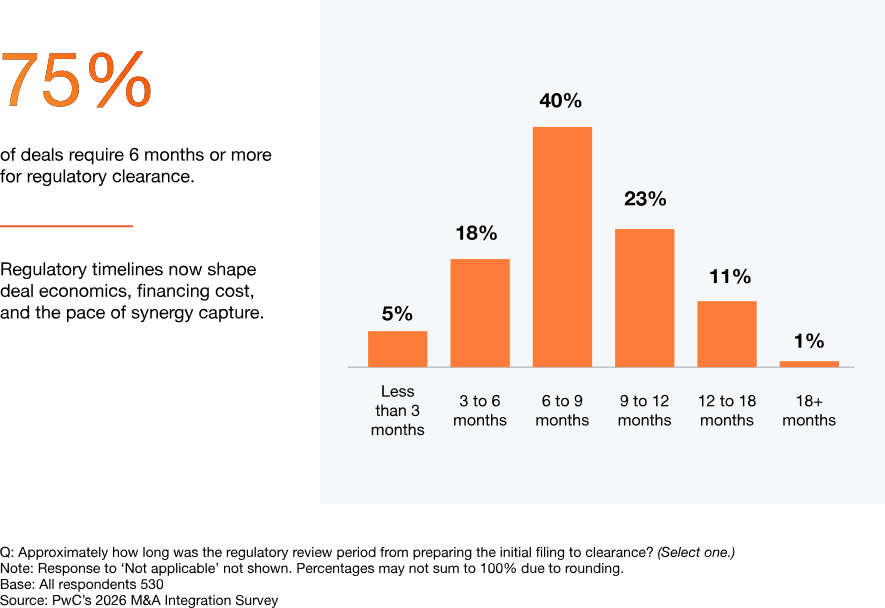
Regulatory strategy is usually a value-protection and deal-certainty discipline rather than a direct value-creation lever. Three in four deals in the survey results required six months or more for clearance, and more than one in three deals took nine months or longer. The practical decision is whether the competition narrative, data, remedy scenarios, and operating implications are developed before the process forces reactive choices.
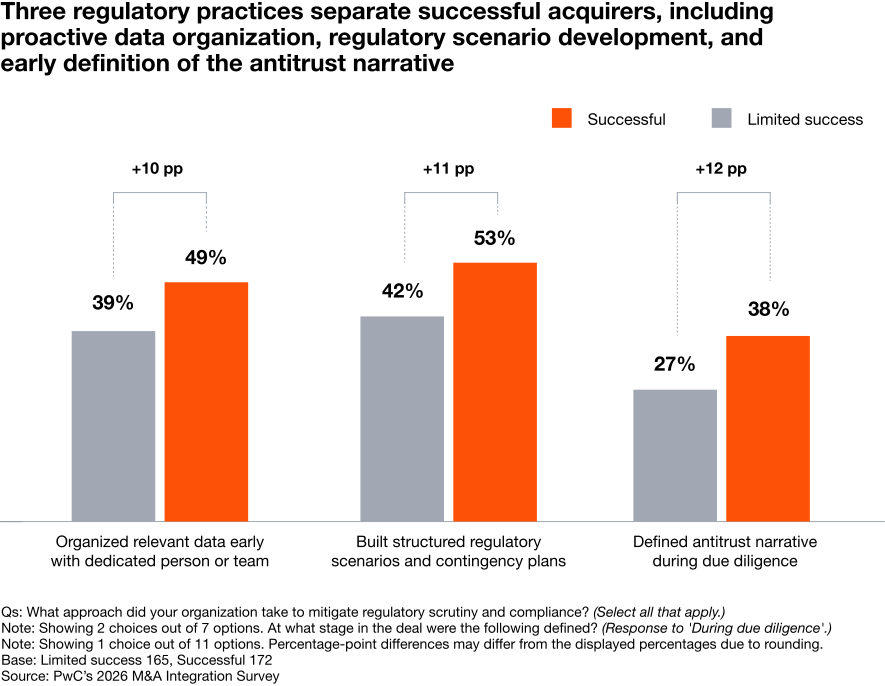
Successful acquirers were 12 percentage points more likely to define core antitrust narratives during diligence and used structured regulatory scenario planning at 1.25 times the rate of peers. Where regulatory risk is material, early scenario planning can preserve optionality, reduce execution uncertainty, and protect the value case as the approval process unfolds.
The agenda is deliberately short. It is not a project checklist. It is the set of questions leadership should answer before the integration plan becomes a collection of workstreams.
THE TEST. If the leadership team cannot name the few changes that matter most, the integration plan is not ready. If it can name them but cannot assign owners or prove value, the thesis is still only a hypothesis.
The survey findings do not point to a universal integration formula. They point to a discipline. The best acquirers do not assume that an integration team will discover the right answers after close. They identify the decisions that are specific to the deal thesis, make the important ones early, and build accountability and measurement around them.
The most successful acquirers will be the ones that make the critical choices their thesis requires, turn those choices into owned commitments, and prove the resulting value. The work starts before Day One: architect the company the deal was meant to create.
THE CENTRAL CLAIM. The strongest acquirers decide, before Day One, what the combined company must become to deliver the deal thesis.
PwC's 2026 M&A Integration Survey captures the perspectives of 530 C-suite executives and senior dealmakers across six industries: consumer markets; energy, utilities and industrials; financial services; health industries; industrial products; and technology, media and telecommunications. Respondents reported firsthand knowledge of a merger or acquisition transaction in which they were involved within the past three years.
Successful acquirers are respondents who reported being completely successful in achieving all identified deal thesis objectives. Partial-success and limited-success acquirers achieved some, or limited/no, prioritized objectives. The survey findings are based on respondent-reported outcomes and should be interpreted as associations rather than causal estimates. All percentages in this report are from the PwC M&A Integration Survey 2026 unless otherwise stated.
{{item.text}}
{{item.text}}