

{{item.videoDuration}}
{{item.title}}
{{item.text}}

{{item.videoDuration}}
{{item.text}}
Just a few years ago, artificial intelligence (AI) in the automotive industry was seen as a futuristic concept—exciting, but distant and siloed in labs or small pilot projects. Today, AI is no longer a side experiment. It has become one of the driving forces behind a fundamental transformation, sweeping through the entire automotive ecosystem.
Behind the scenes, billions of dollars are flowing into AI—from industry leading autonomous driving capabilities to smart manufacturing lines and intelligent customer services. Between 2021 and 2025, the industry announced over $80 billion in AI investments. Early 2026 alone saw nearly $30 billion more committed. These aren’t isolated bursts of innovation, but deliberate, strategic bets signaling that AI is now a core pillar of product development, operations, and customer experience.
What’s fueling this surge? It’s a recognition that the vehicles of tomorrow may no longer be defined by horsepower or hardware alone, but by software and data. Many companies are building software-defined vehicles that learn, adapt, and improve continuously through AI-enabled software platforms.
This adds new competitive pressures to the automotive market. Our proprietary PwC data reveals a growing divide between those that have embraced AI as a foundational business strategy and those still figuring out where to start. The question is no longer if AI matters but who will move faster, scale smarter, and capture the value AI can help unlock.
For OEMs and suppliers, the opportunity is clear but there’s an urgent need to get technology applications right—for the long term. The decisions leaders make today about AI investments, use cases, and enterprise integration can shape market leadership well into the 2030s.
One of the more revealing insights from PwC’s research is how investment patterns differ sharply between OEMs and suppliers, and why understanding these differences is critical to shaping your AI strategy.
OEMs lead the AI investment charge, deploying approximately 75% of automotive AI capital with portfolios covering more than 60 unique AI use cases spanning vehicle development, connected services, autonomy, supply chain, and enterprise functions. OEMs leverage their unrivaled control over vehicle data, customer interfaces, and end-to-end platform architectures to integrate AI deeply throughout their operations.
Proprietary analysis indicates that OEMs are investing heavily in vertical AI stacks, including large-scale AI training infrastructure, fleet-wide data platforms, and centralized compute to support evolving autonomous driving and smart cockpit capabilities. Many are advancing “software-defined vehicles”—where AI and software govern nearly every aspect of vehicle operation—effectively transforming cars into intelligent platforms optimized continuously through software updates.
Suppliers, representing roughly 20% of AI investment, take a more focused approach. Their AI programs center on modular, component-level innovations such as perception sensors for ADAS, AI-enabled control units, and AI-enabled manufacturing tools that integrate with OEM systems. Suppliers play an important role as enablers of scalable OEM AI capability but typically lack ownership of full vehicle or data platform ecosystems.
This division of labor creates a layered automotive AI ecosystem. OEMs act as orchestrators of broad AI deployment and owners of software-defined platforms, diffusing AI innovations at scale to customers worldwide. Suppliers innovate intensively within their domains, contributing vital technology blocks that strengthen the OEM platforms.
Companies that clearly define their role and craft AI strategies reflecting their unique strengths and dependencies are better positioned to capitalize on AI’s potential.
A closer examination of AI funding within the automotive industry reveals three dominant areas where investments are concentrated—connected and automated services for software-defined vehicles, R&D and engineering/product development, and operational and expertise. Together, these three account for roughly two-thirds of all AI investment, highlighting the sector’s dual priorities. On one side, there’s a clear focus on developing smarter, safer, and more personalized vehicles through advanced AI-enabled features embedded directly in the car. On the other, there’s significant investment in accelerating product innovation cycles with AI-enabled design, simulation, and validation tools.
Software-defined vehicles (SDVs) are at the heart of a significant shift in automotive AI investment, particularly powering growth in connected and automated services. Unlike traditional vehicles where software is simply an add-on, SDVs integrate software and AI deeply into their core systems. This integration spans critical functions including propulsion, energy management, driver assistance, and onboard entertainment, transforming the vehicle into a dynamic, software-centric platform.
PwC’s analysis suggests that AI investments related to SDVs are heavily product-focused and concentrated in a select set of high-impact areas. Key categories include software architecture, centralized data platforms, autonomous driving capabilities, and connected diagnostics. These investments do more than improve vehicle functionality—they directly enhance vehicle differentiation and create new revenue opportunities through advanced driver assistance features, over-the-air software updates, and usage-based services.
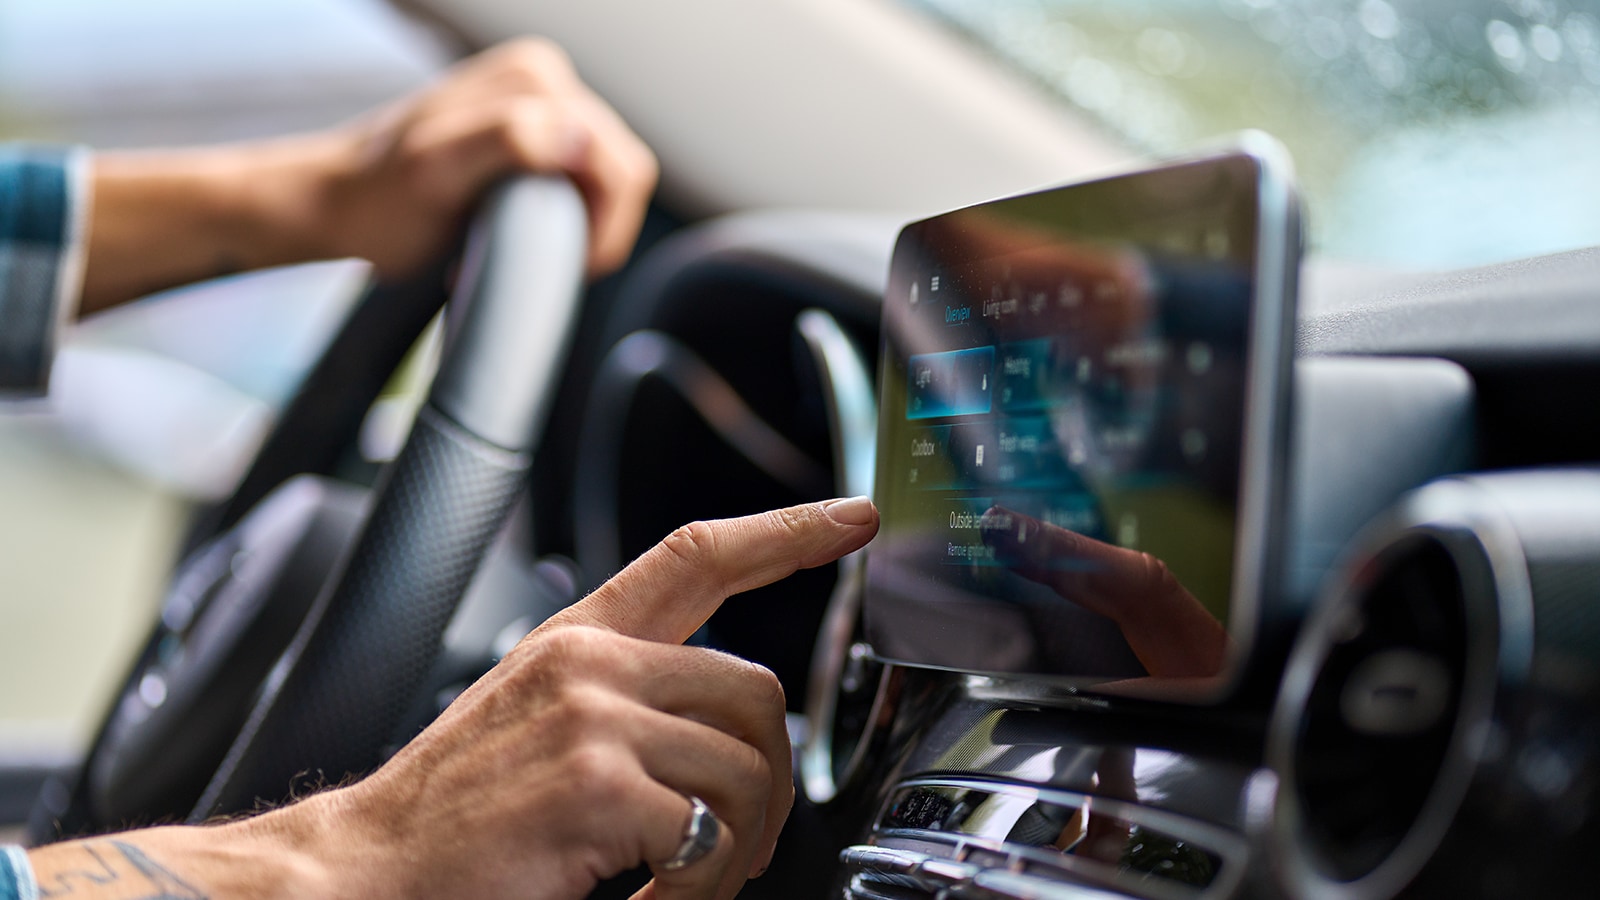
Connected and automated services cover a wide and growing range of applications, including conversational voice assistants, predictive vehicle health monitoring, AI-enhanced traffic and navigation systems, advanced driver assistance systems (ADAS), digital cockpits, and in-cabin monitoring. Together, these technologies turn vehicles from static machines into intelligent, adaptive platforms that continuously learn and improve. The result is more seamless, engaging, and safer driving for users. Beyond functional benefits, this evolution may help drive stronger brand loyalty by embedding AI as an essential, customer-facing element.
Meanwhile, R&D and engineering functions leverage AI to speed innovation in fundamental ways. Technologies such as high-volume virtual prototyping, complex system simulation, automated code generation, development of digital twins, and advanced battery chemistry modeling enable engineers to enhance multiple product variables simultaneously. PwC’s data indicates that this AI infusion can help reduce development timelines from weeks to days or even hours, providing a powerful competitive edge through faster time-to-market and higher product quality.
In addition to these product-centric areas, AI investments extend to operational and enterprise functions such as manufacturing robotics, computer vision-powered quality inspections, warranty and recall analytics, supply chain forecasting, and financial scenario modeling. While the ROI from any single operations-focused AI use case may be smaller compared to product innovations, together these efforts contribute substantially to cost savings, operational resilience, and agility throughout the automotive value chain.
The distribution of AI investment shares underlines AI’s broadening reach from enhancing the vehicle’s immediate user experience to enhancing the complex, interrelated industrial and commercial processes that support it. Successfully navigating this landscape may require many companies to balance focus and investment between frontline product innovation and backend operational excellence to harness AI’s transformative potential.
This distribution underscores the expanding reach of AI spanning from the vehicle experience to virtually every aspect of the underlying industrial and commercial ecosystem.
Unlocking a strong ROI from AI initiatives remains a top priority for automotive industry leaders, yet it’s often one of the most challenging aspects of AI adoption. PwC’s research shows that the financial returns of AI projects in the automotive sector vary significantly based on their focus and execution.
Product-focused AI initiatives—those that enhance vehicle features, improve customer experience, or create new revenue streams—can help deliver substantial ROI, sometimes ranging from 0.7 times up to six times the initial investment. On the other hand, AI projects aimed at operational improvements like manufacturing enhancement, supply chain forecasting, and enterprise support tend to generate smaller but still meaningful returns, generally between 0.5 and two times invested capital.
While the potential upside is clear, many companies struggle to effectively measure AI’s true business impact. Defining consistent, relevant metrics for AI projects is notoriously difficult. Intangible benefits—improved safety, enhanced brand reputation, elevated customer satisfaction—are hard to quantify but play an important role in long-term value creation. Moreover, the downstream effects of AI—cost savings from reducing recalls or generating recurring revenues from AI-enabled vehicle services—often reveal themselves over time and can be overlooked in short-term evaluations.
PwC’s experience highlights that embedding ROI measurement early in AI implementation can be essential for success. Organizations that align AI initiatives with clearly defined, quantifiable key performance indicators (KPIs), establish strong baselines before implementation, and continuously track progress can be better equipped to justify further investments and scale successful projects.
Ultimately, disciplined and transparent ROI tracking transforms AI from a speculative technology experiment into a trusted driver of business growth and operational efficiency. Companies that embrace rigorous evaluation practices are positioned to unlock the value of AI and maintain momentum in this rapidly evolving landscape.
The automotive AI race is accelerating but the path is complicated by many short-term headwinds like geopolitical instability, rising energy costs, supply chain volatility, and capital constraints.
At the same time, these complications reinforce the vital role AI can play—from predictive analytics that alert supply disruptions early to AI-driven flexible manufacturing lines that adapt in real time.
Product-focused AI investment share to increase to 75% by 2035 from roughly 60% today.
PwC forecastsMeanwhile, sustained high oil prices and shifting consumer preferences are accelerating electric vehicle (EV) adoption—the most inherently software-defined platforms today and for the foreseeable future. PwC forecasts an increase in product-focused AI investment share from roughly 60% today to nearly 75% by 2035.
Those who delay risk allowing faster, more focused competitors to seize AI’s advantages—whether reducing costs, speeding innovation, or creating thrilling new customer experiences.
Automotive AI leadership is no longer a visionary aspiration—it’s a race defined by clear winners acting today. Owning the vehicle’s software stack, delivering distinctive AI-enabled customer experiences, accelerating engineering innovation, and transforming operations with AI-powered agility may create a durable competitive advantage.
PwC’s proprietary data demonstrates that success comes to those who advance beyond fragmented pilots and isolated point solutions. Instead, leadership demands holistic, integrated AI programs scaled across vehicles, factories, and the enterprise.
OEMs and suppliers must assess their AI maturity honestly, sharpen investments toward highest-value use cases, and make a long-term commitment to transformational change underpinned by rigorous business metrics.
The opportunity is immense, but so are the challenges. The companies that win the race will be those that harness AI to drive value not only in the lab but in every vehicle on the road and every process behind the scenes.
This article uses PwC’s proprietary automotive AI use-case database, quantitative investment modeling, and extensive benchmarking across leading OEMs and suppliers worldwide. It reflects insights from cross-industry research initiatives combined with deep sector expertise—providing a uniquely comprehensive, data-driven lens on how AI is reshaping automotive innovation and operational excellence.
{{item.text}}
{{item.text}}


