Turn insight into action
We help you solve the problems that matter most so you can act faster and move further.
What would you like to explore?
Can electric mobility shift into a higher gear?
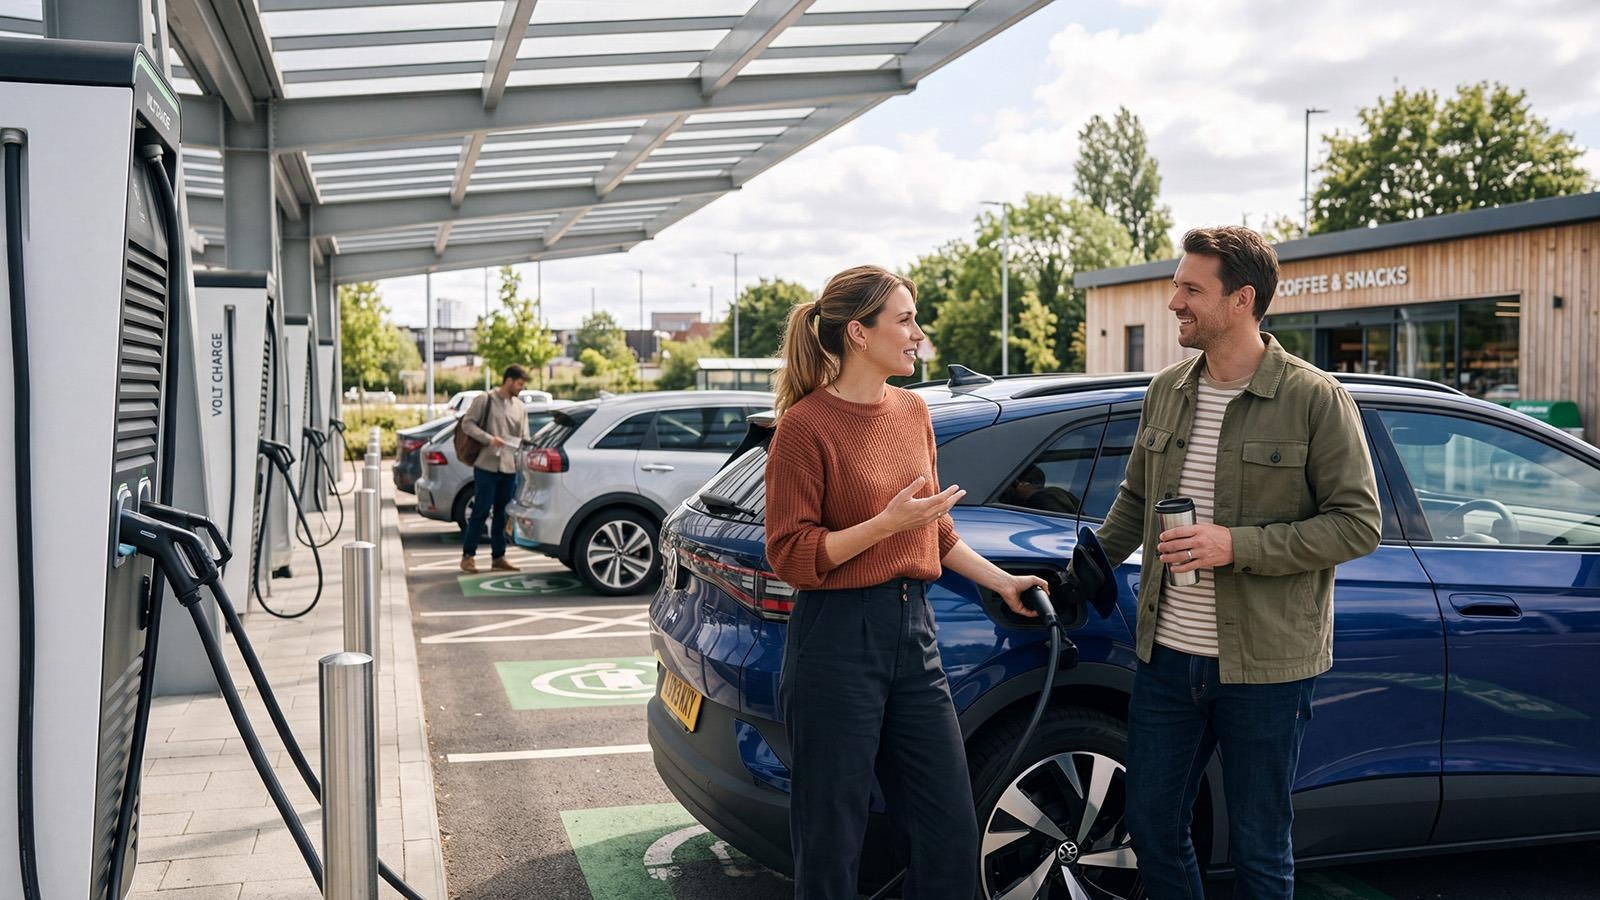
Further progress will hinge on the auto industry’s ability to convince prospects to take the EV plunge.
The takeaways
- 62% of global consumers intend to buy an electric vehicle (EV) within five years, with rising fuel prices increasing interest, but charging duration and battery lifetime remain key barriers to adoption.
- Mainstream prospective EV buyers, not just tech enthusiasts, are now key to EV growth. They tend to value price and quality over environmental motivations.
- Norway, the Netherlands, Sweden, and China score the highest ratings on PwC’s eReadiness Index.
The global electric mobility transition, which is really a series of country-by-country and regional transitions, is picking up pace. A combination of economic, technological, and geopolitical factors is making an EV purchase look like a desirable choice for consumers in most markets. According to PwC Autofacts, in the first half of 2026, global EV sales rose 9% from 2025. In July, the International Energy Agency forecast that EV sales will account for a record 29% of annual global car sales in 2026. Some of the increased demand is being influenced by government policies limiting road-based carbon emissions and offering incentives to buy EVs. The spike in fuel prices because of the conflict in the Persian Gulf also has made the economic benefits of operating EVs more apparent.
Further gains will materialise only if consumers, automakers, policymakers, and the broader mobility ecosystem are adequately prepared. What are the specific pain points that are keeping the 91% of car owners who have yet to purchase an EV from taking the plunge? What are the expectations of potential EV drivers when it comes to range, charging, and cost? And what are individual countries doing to support supply, demand, and the build-out of necessary infrastructure?
PwC’s eReadiness Survey 2026 is based on the responses of 19,000 private automobile customers in 31 markets across three regions: Asia-Pacific (APAC); Europe, the Middle East, and Africa (EMEA); and the Americas (specifically, Brazil, Canada, and the United States). It takes stock of evolving consumer preferences and concerns, and points to issues the auto industry can focus on to grow the overall EV market. Broadly speaking, the key to accelerating growth will be reducing the friction and obstacles that consumers face in charging, fuelling, and operating EVs when compared with the century-old technology and infrastructure surrounding the internal combustion engine (ICE).
Conversion opportunities
Convincing EV prospects to become EV owners
Of those who have purchased EVs, the overwhelming majority—82%—say they are satisfied with their vehicles. In EMEA, the majority (54%) cite the overall driving experience as the top reason for their satisfaction. In APAC, owners like the operating cost. In the Americas region, 50% say charging duration is the best attribute of ownership. In only two countries, Japan and Thailand, are owner dissatisfaction ratings as high as 15%. Compared with ICE owners, EV owners are more satisfied (45% to 37%) with the overall purchasing process.
The wide-open white space for the EV market is the 91% of consumers who don’t yet own EVs and, in particular, the 62% of people who have declared their intention to buy an EV in the next five years. The proportion of prospects is highest in populous emerging markets like India, Indonesia, the Philippines, and Vietnam, at 82%. Saudi Arabia, Qatar, and Turkey are close behind at 81%. The true outliers among wealthy economies are two markets where the electric mobility transition remains stuck in a low gear. In Japan, 64% consider themselves sceptics and only 32% are prospects, perhaps because domestic automakers continue to focus on hybrid technology. In the US, where policy moves and consumer preferences continue to favour the ICE, only 45% are prospects and fully 49% are sceptics. Eastern European nations like Slovakia and Czech Republic also have a relatively low percentage of prospects.
Prospects don’t want to buy EVs to save the world. They want to save money and time. The primary motivations to buy an EV among all prospects remain consistent with last year’s survey. The top three are better fuel economy (61%), the convenience of charging at home (40%), and lower overall maintenance costs (31%). As for price, in the Americas, 72% expect to purchase an EV for under €40,000; in EMEA, the proportion is 64%, and in APAC, only 59%.
Addressing concerns
Overcoming charging obstacles and range anxiety
The two main challenges prospects cite have to do with the fundamental factors that make the experience of owning and operating an EV different than owning and operating a traditional car: charging and range.
The inconvenience, unavailability, and occasional hassle of using public charging infrastructure is clearly a challenge. Our survey finds that 71% of owners have private parking spaces, and charging at home is the predominant mode of refuelling in every region. In APAC and EMEA, the slowly increasing use of public charging facilities may reflect rising regional investment in that infrastructure. When asked about the key sources of dissatisfaction surrounding public charging, EV owners cite charging point location, the time it takes to charge, and the cost as the highest-priority issues. They are also frustrated by the etiquette of their fellow motorists. 34% of owners complain that charging points are occupied by vehicles not currently being charged.
Even though the driving distance of EVs continues to improve, range anxiety remains a concern. 72% of owners experienced a reduction in miles covered due to extreme heat or cold. Weather-induced issues are exacerbated by the time and effort it takes to recharge. Nevertheless, 54% of owners say that an EV still fully meets their current driving needs and 60% say weather-related range anxiety wouldn’t affect their buying decision in the future.
Prospects register the same concerns as owners, but in noticeably higher numbers. When prospects were asked about the main obstacles deterring them from purchasing, the most frequently cited factors were charging duration (46%), doubts about battery lifetime (44%), upfront costs (36%), and range anxiety (34%). Just over 50% consider 300–400km an acceptable driving range provided they could charge in under 30 minutes, while only 18% said 200–300km was acceptable.
72% expect a charging time of under 30 minutes. Rapid charging points can deliver that speed, but home charging typically takes much longer. Consumers have different expectations on charging times depending on where they live. Half of the prospects in France and Italy expect to charge their vehicle in less than 24 minutes, for example, while half of those in the Philippines are willing to wait up to 53 minutes.
Despite the inroads made by EV manufacturers, plenty of sceptics remain. They share the same concerns, at essentially the same rate, as prospects, citing charging time (49%), battery lifetime (46%), range limitation (37%), and higher upfront costs compared to ICE vehicles (28%). Drivers in Brazil and Japan are the most concerned both about battery lifetime (58%) and charging time (57%). Those in Canada (47%), the US (45%), and India (45%) have the greatest range anxiety, likely due to the long distances drivers in those large countries need to cover on a regular basis.
Our survey also surfaces scepticism about another set of technologies transforming mobility. Autonomous driving is still in its infancy in most regions. To be sure, the momentum over the last 12 months has been remarkable. There have been technical advances, and commercial applications (particularly in the US and China); pilot projects in Europe, the Middle East, and other regions; and regulatory initiatives in numerous jurisdictions. The focus is often on the US and China, where automated driving in private cars and robotaxis are most advanced. Against this backdrop, one finding from our consumer survey seems counterintuitive: EMEA consumers show a higher awareness of autonomous mobility and willingness to try it, compared with consumers in APAC and the Americas. To answer the many unanswered questions surrounding autonomous mobility, PwC is launching a new study—“AV Readiness”—this winter.
Global view
How eReadiness looks around the world
Our annual survey evaluates the mobility eReadiness of countries around the world based on four main criteria.
The index rating is an average of numerical ratings for the four components with 5 being the top ranking. Using these criteria, countries in northern Europe such as Norway (4.4 out of 5), the Netherlands (3.9), Sweden (3.7), and the United Kingdom (3.4), along with China (3.7) and Switzerland (3.4), have the highest eReadiness Index scores. Saudi Arabia (2.3) Japan (2.1), India (2.0), South Africa (1.9), and Malaysia (1.7) score on the lower end of the scale.
This second part of the survey echoes the consumer viewpoints of the first. Namely, that countries currently suffer from an EV infrastructure weakness that is inhibiting potential demand for new vehicles even where there is a good supply available. Current owners, prospects, and sceptics alike all share the same concerns that the infrastructure is not sufficiently mature or functional.
In Japan, for example, ecosystem attractiveness is 4.0 but infrastructure ranks at just 1.5. It’s not surprising, then, that demand for EVs is just 1.8 and the country’s overall eReadiness languishes at 2.1. Even Singapore, where the government’s generous financial incentives pushed the demand to a score of 4.8, struggles with its infrastructure (2.6). In western Europe, infrastructure capability lags behind both demand and supply of EVs in Italy and Spain.
Norway’s leadership status can be attributed to its government’s ongoing commitment to build infrastructure and cultivate demand through purchase incentives for EVs, which now account for 99% of new vehicle registrations. The Netherlands, which ranks second overall on our index, and where over 45% of new cars sold are EVs, stipulates that all new passenger vehicles, in line with its national climate policy, must be zero-emission by 2030.
China is already the world’s leading EV market. According to the International Energy Agency, Chinese consumers are on course to purchase 14.3 million new EVs in 2026, accounting for 61% of global sales. Vietnam is the fastest-growing EV market in southeast Asia, thanks in part to government incentives, including exemption from registration fees for EVs through 2027.
Among countries at the tail end of the index, Japan’s EV adoption continues to be hampered by supply issues mainly because of its domestic automakers’ commitment to petrol hybrid technology. It also suffers from a lack of charging infrastructure. Supply, demand, and infrastructure issues still hold India back, though today’s high oil and gas prices (in a country that imports nearly 90% of its oil) are starting to spark change. EV sales grew by 25% in the year ending March 2026 and now command more than 5% of India’s vehicle market. As for South Africa, the high prices of EVs (including a 25% import duty) compared to ICE equivalents (18% duty) hurt ecosystem attractiveness and are the largest barriers to consumer adoption.
Making progress
Improved user experience drives growth
The findings from the 2026 eReadiness Survey offer encouragement to everyone invested in the growth of the global EV market. The supply of vehicles is no longer a major issue. China, the world’s largest EV manufacturer, has excess domestic capacity and is increasing its exports throughout the world. 16 of the 31 countries surveyed have supply scores of 2.5 or higher, and these figures will surely improve in the coming years. Demand for EVs also is strong—especially where governments provide incentives to switch from ICE vehicles.
The sticking point for widespread EV adoption remains the concerns that owners share about charging facilities, the time it takes to recharge, and range anxiety. These are infrastructure and ecosystem issues that must be addressed if mainstream prospective owners are going to embrace EVs.
Improved battery technology is already helping overcome consumers’ doubts about range anxiety. But government and industry will need to prioritise expanded charging infrastructure if current prospective EV owners are to enjoy the same ease of driving experience that they have with ICE infrastructure. It’s worth noting that the original motor vehicle revolution would never have happened had it not been for the massive public and private investment in both a road network and refuelling service stations.
The current barriers to adoption are surmountable. Overcome them and a whole new market of prospective owners are ready to buy in.
Related content
Driving the automotive industry into the future
PwC’s survey highlights the capabilities and strategies automotive companies must develop to gain a distinct advantage in the years ahead.
24 min read
The future of how we move
Discover how grassroots innovations are rewiring mobility—from streets to supply chains.
What does the future of mobility look like?
The way we move people and things is changing—transportation is becoming more electric, more autonomous, and more informed by advanced technology.
Get in touch
Patrick Amberger
Director, PwC
Strategy& Germany
Iacopo Neri
Director
PwC Italy
Francesco Papi
Partner
PwC Italy
