
From AI ambition to enterprise value: The evolving CIO mandate in the GCC
EMEA CIO Survey 2027: GCC findings
The Chief Information Officer (CIO) role now extends well beyond managing IT infrastructure and keeping systems running. As AI investment accelerates across the GCC, organisations expect CIOs to work more closely with the business, orchestrating technology, AI and people as part of a broader enterprise mandate. This shift is not waiting for 2030 – it is already underway.
Foreword
Across the key economies of the Gulf Cooperation Council (GCC), artificial intelligence (AI) is moving beyond pilots and experiments and into the operating heart of organisations. Investment remains strong. Expectations are high. Now boards are asking sharper questions about value. As the focus moves beyond adoption, the chief information officer is expected to show how technology investment translates into business outcomes.
So, is the role of the CIO changing? Is the CIO moving closer to the centre of business strategy?
In the GCC, the share of technology leaders who see the orchestration of technology, AI and people as their primary mandate is expected to rise from 35% to 45% within the next 12 to 18 months. At the same time, technology leaders are being judged not only by how well technology performs, but by the business outcomes it creates.
This shift is being shaped by the region’s own priorities, ambitions and operating context. In the GCC, governments have placed digital transformation and AI at the heart of national growth agendas. Organisations have invested heavily in infrastructure, platforms and talent. Technology leaders in the GCC, confident than many of their peers in the wider Europe, the Middle East and Africa (EMEA) region in both organisational and workforce readiness, are therefore asking deeper questions about cyber resilience, trust and digital sovereignty; about the convergence of IT, operational technology and R&D; and about how technology choices shape operational resilience and strategic autonomy.
These are not side conversations. They are becoming part of the architecture of growth. By 2030, these forces are likely to pull the CIO even further into the business. Nearly seven in 10 GCC respondents believe the next generation of CIOs is as likely to come from a business background as from traditional IT. That signals that business fluency, operating-model design and value creation are becoming just as important as technical depth.
Few regions combine such strong investment appetite, policy momentum and willingness to embrace emerging technologies as the GCC. The challenge for the future CIO, will be to convert that momentum into disciplined, resilient and purposeful execution. This survey points to where that work must begin. The region has shown that it is prepared to invest in the future. The next few years will determine how effectively its CIOs can bring that future to life – consistently, across the enterprise and at scale.

Bivek Sharma, Chief Technology and AI Officer, PwC Middle East
Key findings
Investment is laying the foundations for transformation: 93% of GCC CIOs surveyed expect AI spending to increase, yet only 21% are scaling or have embedded transformation across the enterprise so far.
AI confidence is high, but scaling barriers remain: 59% of respondents believe their data, platforms and governance are ready to scale AI, yet 47% cite legacy integration and 45% highlight ineffective governance as barriers to scaling AI agents.
Technology leaders are accountable for business outcomes: 43% of regional technology leaders surveyed expect IT to be measured primarily on business outcomes within 12 to 18 months, up from 16% today and ahead of 33% in EMEA.
Orchestrating a hybrid workforce of humans and AI agents is emerging as a key priority: 46% of GCC CIOs surveyed rank it among the top three factors impacting their role by 2030, compared with 39% across EMEA, reflecting a shift from managing technology to orchestrating people, AI and business operations.
Skills remain a bottleneck despite high workforce confidence: 62% of survey respondents believe their workforce has the skills to maximise AI value, versus 39% in EMEA, yet 46% cite skills and talent as a barrier to scaling AI agents and only 23% prioritise AI training investment.
The next CIO may come from a business background: 69% of GCC respondents believe the next generation of CIOs is as likely to come from a business background as from traditional IT, compared with 54% in EMEA.
Section 1 The CIO mandate is being redefined faster than organisations can adapt
“What’s striking about the GCC right now isn’t the appetite for AI, it’s the sheer scale of it. Budgets are rising faster than almost anywhere else, and organisations are more confident in their foundations than EMEA peers. But that confidence is running ahead of the data and governance work still needed to justify it. Closing that gap is the real test ahead.”
We asked GCC technology leaders an open question: what do CEOs and their boards most underestimate about how the CIO role must change between now and 2030? AI and data integration came up most often, but most answers weren’t about technology at all. Respondents talked about governance and risk, strategic business partnerships, organisational change and talent. That makes leading transformation, not simply delivering technology projects, an increasingly important measure of the CIO role.
In their words, technology leaders don’t simply manage IT anymore; they shape the business itself. But this shift depends on people, operating models, and a change in organisational culture, which boards currently underestimate.
By 2030, the CIO mandate will move even closer to the heart of enterprise value creation. It will extend beyond managing technology to shaping how the organisation creates value - orchestrating people, AI, platforms and business teams through a more integrated operating model.
The expanding CIO mandate
Across EMEA, nearly four in 10 technology leaders (38%) expect enterprise-wide transformation to be their primary mandate within 18 months, up from one quarter (25%) today. In the GCC the shift is slightly different. Here, the share of technology leaders who see the orchestration of technology, AI and people as their primary mandate is expected to rise from 35% to 45% within the next 12 to 18 months, while the share of CIOs whose primary mandate is enterprise-wide transformation in the region rises from 16% to 23% within 18 months.
When technology leaders were asked, as part of the survey, how they expect their IT to function in 18 months, four distinct operating model archetypes emerged.

The right model will depend on business demand, the degree of differentiation required, available skills and the organisation’s risk appetite. CIOs may combine capabilities embedded in enterprise applications, standalone solutions and specialist in-house agents, supported by shared orchestration and controls. These models are not necessarily fixed: organisations may move from one to another as demand, capability and maturity evolve. More internal development, however, is not in itself evidence of greater value, the test is whether the operating model improves business outcomes.
In the GCC, the dominant aspiration is the Amplifier model (48% of respondents), where IT remains the primary builder, but uses AI to increase delivery capacity - enabling existing teams to do more without a proportionate increase in headcount. This is different from EMEA where the Enabler model leads.
Among GCC respondents, 44% also aspired to the Enabler model, where business units become the primary builders and IT provides platforms, governance and AI guardrails. The Builder model (7%) involves sharp increases in in-house development by both IT and the business. And the Optimiser model (1%) focuses only on efficiency-driven IT, but almost nobody is aiming for this.
Currently, 44% of GCC respondents report directly to the CEO, president or the board, placing the CIO closer to the centre of business strategy. As boards seem to judge technology leaders on business outcomes rather than technology delivery alone, the profile of the role is also changing. Some 69% of GCC respondents say the next CIO is as likely to come from a business background as from IT, compared with 54% across EMEA. Business fluency is becoming as important as technical expertise.
“CIOs will need much stronger financial and business expertise. Technical decisions will have direct implications for business growth and shareholder value, making financial literacy as important as technical knowledge.”
Ambition is outpacing organisational readiness
The expansion of the CIO mandate is not yet matched by organisational readiness. Across the GCC, 47% of regional respondents indicated that organisations are still focused on building the core capabilities needed for the CIO to orchestrate how technology, AI and people can work together to deliver business outcomes. A further 25% of survey respondents said the direction is set but execution is at an early stage; while another 7% say they are fragmented and reactive with no enterprise-wide direction. Only 18% are scaling transformation with measurable impact, and just 3% say transformation is already fully embedded and delivering value.
Many organisations in the GCC are building the capabilities needed to deliver on the 2030 CIO agenda.
Q: Which of the following best describes your organisation’s current level of readiness for the CIO 2030 agenda?

What separates the organisations furthest ahead on the 2030 CIO agenda is foundations. Those further along consistently report stronger confidence in their data, platforms and governance; those still setting direction or building core capabilities report markedly less.
The operating model also holds back organisations: 44% of GCC respondents rank operating model and change management as a top-five barrier to scaling agents. This tracks closely to 42% of EMEA respondents.
“For CIOs, the biggest challenge is helping people adapt to new ways of working by changing decision-making processes, accountability structures, and attitudes toward risk.”
AI is reshaping the enterprise
AI now tops both the boardroom agenda and the budget. In the GCC, AI and agentic automation lead IT spend, with 67% of regional technology leaders ranking these in the top five areas of spend, followed closely by cyber, trust and sovereignty transformation (currently 56% and rising to 59% in 18 months). This suggests that the region may be moving beyond a pure adoption agenda towards one that also prioritises the trust, resilience and control needed to scale AI.
That ambition is matched by confidence. GCC technology leaders are more likely than their EMEA peers to believe that their data, platforms and governance are ready to support AI at scale: 59% say their data, platforms and governance can already support and scale AI, compared to just half (50%) in EMEA.
Earlier this year, when PwC engaged with business leaders in the region, as part of the 29th Global CEO Survey,1 72% of GCC CEOs indicated they had clear roadmaps for their AI ambitions, indicating that organisations in the region are investing heavily, confidence is high and AI roadmaps are increasingly well defined.
Section 2 Four challenges stand between CIO ambition and delivery

“Realising AI’s value, building trust, achieving technology convergence and preparing the workforce are not four separate challenges. They are symptoms of the same underlying problem: organisations are adopting AI faster than they are changing how they work. The real opportunity lies in rethinking how decisions are made, how teams collaborate and how people develop new capabilities. Get those foundations right, and progress on all four fronts becomes possible.”
Despite high levels of confidence, nearly a third of those GCC CEOs PwC engaged with as part of its 29th Global CEO Survey,2 were concerned that their businesses are not transforming fast enough to keep pace with technological change. That has put the CIO under growing pressure. As the role moves closer to the heart of business transformation, technology leaders are facing four distinct challenges:
Workforce readiness: Investment in skills lags demand
Value and economics: Measurement hasn’t caught up with spending
Scaling and trust: Governance struggles to keep pace with pilots
Technology, convergence and digital sovereignty: Information technology, operational technology and research and development remain insufficiently integrated.
These challenges go beyond technology. They affect how decisions are made, how teams work together and where accountability sits across the organisation. Addressing them will require CIOs to think about how they can strengthen governance, clarify ownership and enable technology, people and the wider business to work more effectively together.
Workforce readiness
GCC technology leaders are notably more confident than their EMEA peers, with 62% of respondents indicating their workforce has the skills needed to maximise value from AI, compared with 39% across EMEA. Four in five (80%) also say their organisation is upskilling employees at the pace required, versus 66% in EMEA.
Yet the investment picture points to a potential disconnect. Lack of skills and talent is a top-five barrier to scaling AI agents, cited by 46% of GCC respondents, but improving employee training and skills rank last among seven AI investment priorities, cited by 23%, compared with 32% across EMEA.
As AI moves from adoption to scale, organisations may need to ensure that investment in skills keeps pace with the demands being placed on their people. More than half (55%) of GCC tech leaders surveyed indicated that AI skills are currently developed jointly by IT and business, rising slightly to 57% in 18 months. But there are signs of a modest shift: the share of respondents who expect the CIO or IT function to lead AI skills development rises from 17% today to 21% over the same period. This suggests that as AI adoption expands, technology leaders may take a more active role in coordinating enterprise-wide capability building.
The stakes rise as the operating model changes: 44% of GCC technology leaders expect business units to become the primary builders of technology, with IT providing the platform and guardrails. This is in line with 45% of EMEA respondents. However, this does not necessarily mean IT's delivery role is diminishing. With 48% of respondents expecting business demand for technology to increase, IT may remain a primary builder while using AI to expand delivery capacity without expanding headcount. Making this more distributed model work will require deeper AI capability across the organisation. Currently, practitioner-level fluency sits at just 6% but is expected to rise to 33% in 18 months (compared to 30% in EMEA).
Value and economics
AI budgets are also growing faster than the CIOs’ ability to account for them. While 93% of GCC respondents with visibility of their organisation’s AI budget expect it to increase, one in five (20%) report advanced AI cost-management capabilities. Just 5% link AI spend directly to business value. Most respondents can see where the money is being spent, but far fewer can demonstrate what that investment is delivering. For CIOs, the pressure to show returns is likely to intensify.
“By 2030 the CIO won’t just keep systems secure, they’ll own model risk, AI costs, and how agents make decisions across the business… co-owning P&L with finance as AI spend becomes volatile.”
Very few organisations can actively forecast and optimise costs
Q: Which of the following best describes your organisation’s current ability to track, forecast and optimise AI-related costs (including tokens, inference, training and agent consumption)?

“By 2030 CIOs will be increasingly measured on their ability to create quantifiable business value. Their success will depend on linking technology initiatives directly to revenue growth, customer satisfaction, and enterprise performance.”
The CIO scorecard is, therefore, changing. The share of GCC respondents who expect IT to be measured primarily by business outcomes will nearly triple over the next 18 months, from 16% to 43%. That compares with a rise from 16% to 33% across EMEA. The shift marks a move away from traditional measures such as uptime and service levels towards a stronger focus on business impact, reflecting the CIO’s expanding role in enterprise transformation.
Scaling and trust
Scaling is where the returns are. GCC technology leaders already rank AI and GenAI use cases as the single most important driver of business growth over the coming 12 to 18 months (59%), ahead of any other technology priority. However, unlike EMEA, where scaling use cases is the top AI investment priority, GCC respondents are prioritising improving decision making (57%) and building AI foundations (56%) ahead of scaling AI use cases (42%).

But the barriers to scaling AI agents also come down to trust.
In practice, three questions will determine whether organisations can move from experimentation to enterprise-wide deployment:
Can you satisfy the regulator? Compliance and regulatory constraints are the joint highest barrier cited by 47%.
Can you connect AI to legacy systems? Legacy integration concerns are prominent and cited by 47% of GCC respondents.
Can the data be trusted? Data quality is cited by 44% as a barrier to scaling agentic programmes.

“Boards often underestimate the need for new governance structures to manage autonomous AI systems. Clear accountability and risk management frameworks will be essential as decision-making is increasingly automated.”
Top barriers to scaling agentic AI
The skills picture adds another layer of complexity in the GCC. Security and cybersecurity are the most frequently cited capability gaps limiting the scale-up of AI agents, at 66%, followed by data engineering and data quality at 63%.
This will matter even more as AI is given licence to act on its own. 86% of GCC respondents expect agentic capacity to grow in the next 18 months, while 48% expect agents to outnumber people in at least one function or operational team by 2030.
GCC respondents are also expecting significantly higher growth in their human workforce in 18 months than EMEA peers: 81% expect their IT workforce to grow, compared to 55% in EMEA.
IT operations and software engineering are the most likely destinations for scaled agent deployment (40%), higher than in EMEA (34%), where IT already owns delivery.
As agents move deeper into business processes, trust and accountability become more important. According to the Middle East findings from PwC’s 2027 Digital Trust Insights Survey, only 20% of respondents would allow AI agents full execution autonomy, broadly in line with 22% globally. A further 37% would permit autonomous execution only for lower-risk actions, while another 37% would require human approval before execution. The findings suggest that as agentic AI adoption grows, clear governance, decision rights and boundaries for human oversight will be as important as the technology itself.3
Technology convergence and digital sovereignty
Some of the most valuable AI use cases sit where IT meets the lab or the factory floor. But in most organisations, IT, OT and R&D are disconnected and work in silos. Survey data reveals that respondents with an OT or R&D function in the GCC care about convergence, slightly more than their peers in EMEA (87% vs 81%), but only 22% have reached advanced integration, almost the same as EMEA at 20%.
“As technology delivery becomes decentralised into business and AI tools enable business to function independently, the CIO role will focus more on innovation and governance of the IT stack.”
The challenge is moving from this middle stage of maturity to enterprise-wide convergence. The opportunity, therefore, is not to begin convergence but to deepen it. As agentic AI becomes more embedded in business processes, the ability to connect trusted data, systems and operational context across organisational boundaries will become increasingly important. Organisations that can move beyond integration in individual domains towards more unified platforms and operating models may be better positioned to deploy AI agents across complex, end-to-end processes.
The main barriers to convergence in the GCC are organisational as well as technical. Security, safety and compliance and data interoperability are the leading constraints, each cited by 51% of respondents, followed by organisational silos at 46%. A notable difference from EMEA is the prominence of skills and capability gaps, cited by 42% of Middle East respondents compared with 29% across EMEA.
In addition, geopolitical and sovereignty pressures are becoming an increasingly important consideration in technology-stack decisions in the GCC. Organisations in the region have made most progress on controlling where data sits: 54% say they have standardised or optimised their data sovereignty. This is consistent with the Middle East findings of PwC’s 2027 Digital Trust Insights Survey, where 58% of respondents said they are strengthening in-country or regional data and technology resilience through greater redundancy, while 48% are migrating workloads to sovereign or region-specific cloud providers.4
However, only 30% of the CIO survey respondents in the GCC say they have matured their ability to switch providers and avoid lock-in and just 22% have a mature assessment of the extent of their hyperscaler dependencies.
Section 3 Turning the 2030 CIO agenda into enterprise impact
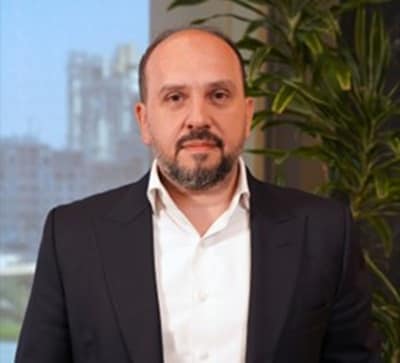
“The next phase of AI transformation will not be defined by how much more AI enterprises deploy. It is about how effectively they convert today’s investments, platforms and capabilities into durable sources of value. Between now and 2030, the defining test for CIOs will be clear: can they turn technological ambition into measurable business impact? Technology remains the enabler, but business value creation needs to be the real goal.”
The most impactful CIOs start with business problems, not technology. They ask where value can be created. The following recommendations will enable CIOs in the GCC to achieve real business value by 2030.
Claim the mandate
The actions outlined in this report will not close the gaps overnight. In the GCC, as organisations grow more comfortable with the strategic case for AI and invest in people and technology, the next challenge for the CIO will be building the data, security, governance and practitioner capabilities needed to translate that ambition into AI at scale. Those that start now will be better positioned to turn ambition into enterprise-wide impact, rather than waiting for the organisation to catch up.
About this report
PwC surveyed 705 senior technology leaders from 22 territories across EMEA to understand how the CIO mandate, technology landscape and enterprise workforce are expected to evolve in the future. For this report, we took a cut of the data from 91 senior technology leaders across three GCC territories (Qatar, Saudi Arabia, the United Arab Emirates).
Data collection took place between 10 July and 6 September 2026. The sentiments captured in the report reflect views at the time of the survey.
Respondents included CIOs, CTOs and other leaders responsible for information technology, AI, digital, product and business transformation. These leaders operate in a range of industries. This report includes selected quotations from respondents in the region, drawn from the survey dataset and presented anonymously.
The survey combined structured quantitative questions - covering mandates, operating models, AI investment, workforce readiness, technology convergence, digital sovereignty and outlook - with an open-ended question asking what CEOs and boards most underestimate about the changes required in the CIO role. Selected quotes appear throughout the report.
The survey was conducted by PwC Research, PwC's global Centre of Excellence for market research and insight.
Contact us
Authors:


Clients and Markets