


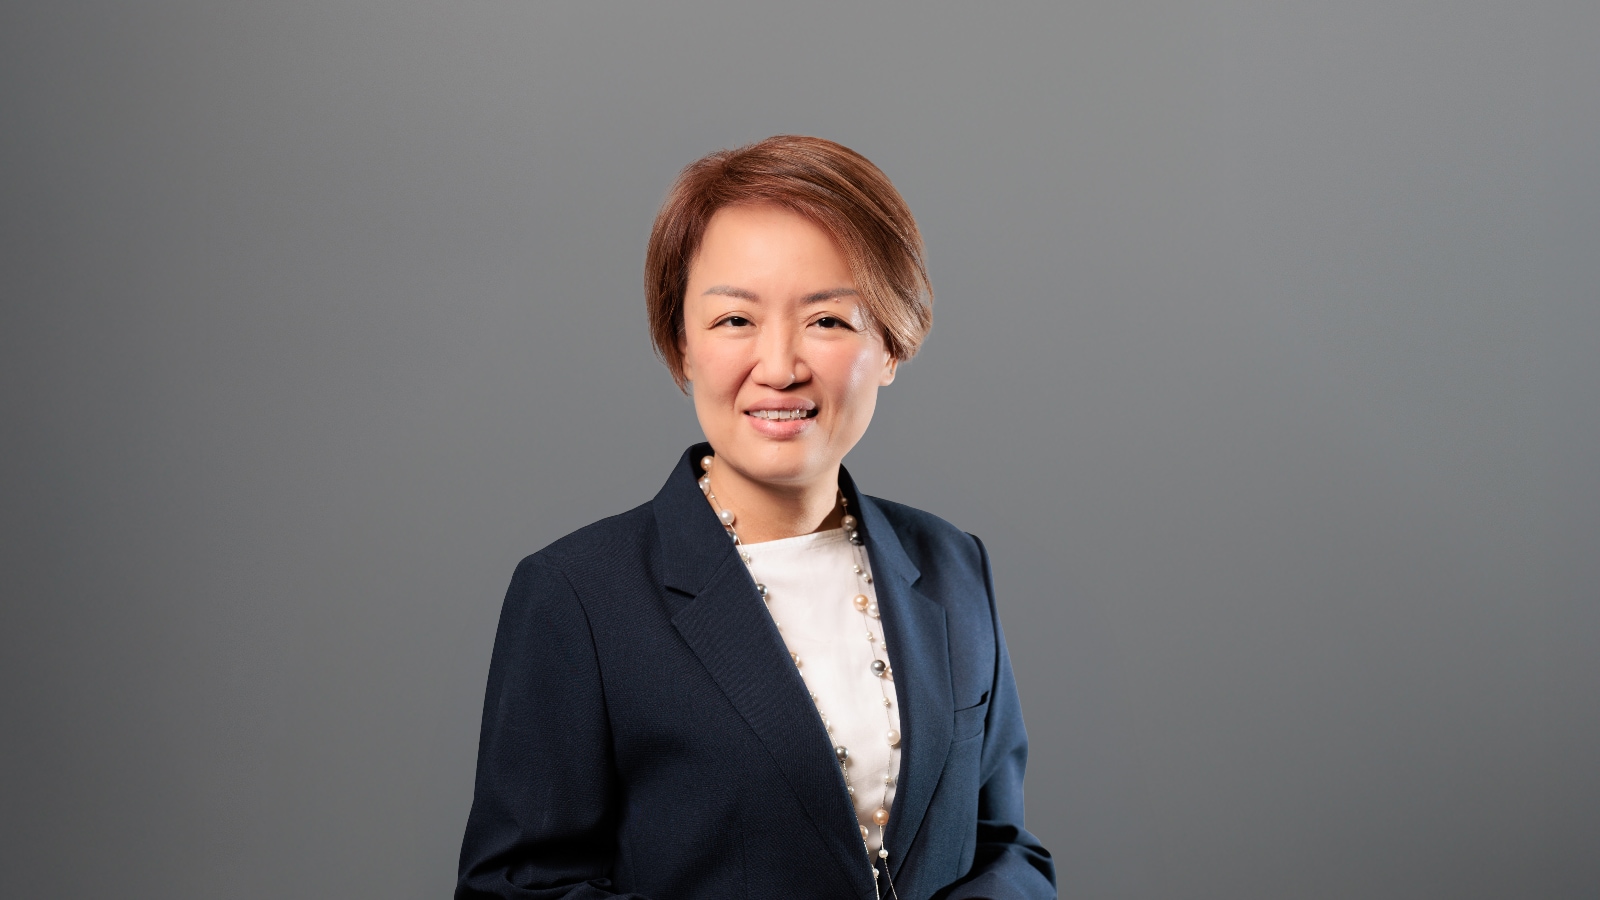
In this edition of Industry Voices, Chan Weng Fai, Deals Partner, and Chong Su Lyn, Deals Director, at PwC Malaysia sat down with Chan Cze Fong, Head of Group Loan Rehabilitation at AmBank Group, to unpack the early warning signs of corporate distress, the judgment calls lenders must make between rehabilitation and recovery, and how to act before vulnerabilities surface.
Foresight beats hindsight
Weng Fai: Public understanding of how banks handle distressed loans is often limited to the broad idea that lenders “chase bad debt.” To set the scene, could you describe what loan rehabilitation is and what falls under your responsibility?
Cze Fong: Most people think loan rehabilitation starts when a borrower misses a payment. In reality, the more important work starts much earlier. To me, rehabilitation is not just about chasing bad debt; it is part of the broader credit risk management discipline. For example, picking up warning signals early, engaging customers in a timely manner, preserving value where the business remains viable, and taking recovery action where rehabilitation is no longer realistic.
The warning signs before the breach
Weng Fai: When a corporate borrower starts having trouble servicing a loan, how does that usually show up and at what point does a file usually land on your desk?
Cze Fong: Distress doesn’t happen overnight. It whispers before it screams. Weakening cash flows, declining profitability, delayed reporting, covenant breaches, deteriorating market conditions, loss of key customers, and operational issues are all signals that deserve attention.
Banks are now far more proactive in managing emerging credit stress. Early Care and Watchlist Management allow lenders to engage customers sooner, understand the issues, and explore practical solutions before stress escalates.
As situations become more complex, accounts are referred to the rehabilitation team to assess the borrower’s financial position, business viability, and turnaround prospects. In many cases, early engagement can make a meaningful difference. It gives both the borrower and the bank more room to assess the situation properly and work on practical solutions.
The work of rehabilitation
Weng Fai: When a corporate file first lands with you and rehabilitation is on the table, what options are usually available, and how do you decide what comes first?
Cze Fong: There’s no one-size-fits-all for restructuring. The toolkit can include rescheduling, refinancing, covenant resets, temporary payment relief, revised repayment profiles, asset disposals, partial settlement, new money, or, in more complex cases, debt-to-equity conversion. The sequence depends on what really is causing the stress.
If it is a timing issue, rescheduling may be enough. If it is a liquidity issue, working capital support may be required. If the business is over-leveraged, then a deeper balance sheet solution may be needed.
Weng Fai: So beyond the financial tools themselves, what has to be in place for a restructuring to be meaningful?
Cze Fong: A real restructuring is more than a new repayment schedule on paper. The borrower needs to provide realistic projections, credible assumptions, and full transparency. Shareholders must show commitment, whether through fresh equity, asset injection, asset monetisation, or other forms of support. Lenders, on their part, should assess the proposal objectively but remain disciplined. Ultimately, the test is not whether the restructuring looks acceptable on paper, but whether the business can survive and service its obligations over the long term.
“Ultimately, the test is not whether the restructuring looks acceptable on paper, but whether the business can survive and service its obligations over the long term.”
Weng Fai: Inter-creditor dynamics are often where restructurings succeed or fail. In multi-bank negotiations, how do you navigate alignment among lenders with different risk appetites, security positions, and exit goals?
Cze Fong: Multi-lender restructurings are often the most challenging because not every lender starts from the same position. They may have different security coverage, provisioning considerations, recovery expectations, risk appetites, and approval timelines. Historically, the Corporate Debt Restructuring Committee (CDRC) has played an important role as a neutral platform to facilitate standstill arrangements, encourage structured negotiations, and help viable businesses reach a coordinated solution outside formal legal proceedings.
As the market moves towards a more industry-led framework, the same principles remain important: early engagement, transparent information sharing, creditor discipline, clear timelines, and practical decision-making. The framework should not become another avenue to delay difficult decisions. It should help lenders come together quickly, test viability objectively, and move either towards a credible restructuring or a timely recovery path.
Weng Fai: How do you measure success in a restructuring?
Cze Fong: Success isn’t just avoiding non-performing loan (NPL) classification or surviving the next repayment cycle. Repayment performance, recovery outcome, and risk reduction are important, but the real test is whether the business has genuinely returned to long-term sustainability. Cash flow often tells a more meaningful story than accounting profits. Some businesses may show profits but continue to struggle with liquidity, while others may report accounting losses but still generate healthy operating cash flows.
Weng Fai: And how do you guard against “extend and pretend” outcomes that simply defer the problem?
Cze Fong: Rehabilitation without discipline is just delayed recovery. Banks need absolute clarity on cash flow assumptions, performance milestones, covenant discipline, monitoring frequency, and trigger points for escalation. No grey areas. No wishful thinking. If the borrower misses agreed milestones, or the business keeps deteriorating, the bank must be prepared to pivot from rehabilitation to recovery without hesitation.
When recovery takes over
Su Lyn: At what point do you conclude that a borrower is no longer a viable rehabilitation case? What financial, behavioural, or strategic signals usually trigger a move to recovery?
Cze Fong: Recovery becomes necessary when reasonable rehabilitation efforts have failed, or when continuing to support the borrower would only erode value further. The common triggers are persistent default, lack of cooperation, asset dissipation, failed restructuring milestones, unsustainable business fundamentals, loss of stakeholder support, or simply the absence of a credible turnaround plan.
Su Lyn: When that happens, how do you decide between out-of-court enforcement, such as security realisation or receivership, and formal insolvency processes like winding-up?
Cze Fong: Once a case moves to recovery, the approach depends on the facts: the type and quality of security, whether there is going-concern value to preserve, the borrower’s conduct, legal timelines, asset valuation, and expected recovery quantum. Out-of-court settlement, asset realisation, receivership, foreclosure, or winding-up may all be considered. Even at this stage, it does not mean every door is closed. If sponsors or shareholders come forward with a serious, clearly funded settlement proposal that gives a better outcome than continued enforcement, the bank should still evaluate it objectively.
Su Lyn: How do you carry out a post-mortem? More importantly, how are those lessons fed back into upstream processes such as origination, credit policy, and early-warning systems?
Cze Fong: Post-mortem is done at the onset upon the account turning impaired instead of at the end of the recovery process. BNM’s emphasis on credit post-mortem is important because impaired credits should not be viewed only as recovery cases. They are also learning cases. The key question is not only “What happened?” but “Could this have been prevented?” Were the original credit assumptions sound? Were the red flags visible earlier? Was repayment capacity overestimated? Did the bank rely too heavily on collateral? Did monitoring pick up the deterioration in time? Could we have acted earlier or differently?
A post-mortem is about strengthening future credit assessment, monitoring, and early-warning practices. The lessons should be fed back into origination standards, sector risk appetite, collateral assessment, covenant design, monitoring triggers, and account management discipline. This is where rehabilitation and recovery work can add value beyond one individual case—by improving the institution’s overall credit culture.
Rehabilitation is not the same as recovery
Su Lyn: Not every distressed borrower can be saved, and not everyone should be. Having seen both paths up close, what ultimately sets apart a borrower worth rehabilitating from one where recovery is the more responsible route?
Cze Fong: The first question I would ask is not simply whether the borrower is in difficulty, but whether the business remains viable. Can it generate sustainable cash flow after the debt is right-sized? Is the management credible and transparent? Are the shareholders prepared to support the business or accept the necessary trade-offs? Are lenders broadly aligned on the way forward?
Some borrowers are under temporary pressure because of delayed payments, rising costs, or short-term disruption. If the underlying business remains sound, rehabilitation may still be appropriate. That is very different from a business facing structural decline, weak governance, poor execution, or lack of shareholder commitment. If there is no credible turnaround plan, or if the restructuring only pushes the problem further down the road without addressing the root cause, then recovery may be the more responsible route.
The machinery of debt and restructuring
Weng Fai: I want to pivot our conversation a little bit. In the current environment, how do you see the role of banks in supporting borrowers facing temporary disruption?
Cze Fong: Middle East tensions are a stark reminder: external shocks hit fast, and they hit hard. Supply chain disruption, higher fuel and logistics costs, currency volatility, softer demand, and tighter liquidity can all put pressure on borrowers. SMEs are usually more vulnerable because they may not have the same cash buffer or flexibility to absorb sudden cost increases.
In that context, BNM’s recent emphasis that banks should continue to support viable borrowers, including corporates and SMEs affected by near-term disruption, is timely. The principle is quite straightforward: support should be given to businesses that are still fundamentally viable, but which need time, liquidity support, or a more realistic repayment structure to get through temporary pressure. For borrowers, the key is to approach the bank early, be transparent on their cash flow position and work together on a solution that preserves business continuity while maintaining repayment discipline.
Weng Fai: If we step back from the individual borrower level, how would you assess Malaysia’s distressed debt and restructuring ecosystem as it stands today?
Cze Fong: Our debt ecosystem has come a long way. We have informal restructuring platforms, court-supervised rescue mechanisms, insolvency processes, and BNM regulatory guidance, each playing a different role depending on the nature and severity of distress. The strength of the system is that there are multiple pathways. Informal workouts are useful when lenders are aligned and the business is viable. Court-backed mechanisms are important when creditor fragmentation or enforcement pressure requires a more formal process.
One practical challenge, however, is the occasional abuse of court process. In some cases, borrowers or sponsors use legal proceedings primarily as a means to delay enforcement and buy time, rather than to address the underlying debt issue. This may include repeated injunction applications, last-minute restructuring proposals, challenges to enforcement steps, or insolvency-related filings that are not supported by a credible repayment or turnaround plan. Borrowers should of course have access to legal remedies, but when the process is used mainly as a delaying tactic, recovery value can be eroded through time, legal cost, asset deterioration, and uncertainty for creditors.
From a lender’s perspective, this means we need to be disciplined in our documentation, decision records, valuation support, and enforcement preparation. We also need to distinguish between a genuine restructuring attempt and a defensive process designed only to postpone the inevitable. A more efficient ecosystem should protect legitimate borrower rights, but at the same time discourage tactical delays that undermine value preservation and creditor confidence.
“A more efficient ecosystem should protect legitimate borrower rights, but at the same time discourage tactical delays that undermine value preservation and creditor confidence..”
The system isn’t the problem. Execution is. Delays in decision-making, unrealistic borrower proposals, fragmented creditor positions, valuation disputes, and enforcement timelines can all erode recovery value. The ecosystem works best when borrowers engage early, lenders act in a coordinated manner and restructuring proposals are tested against commercial reality rather than optimism.
In the time between strain and crisis
If there was a closing lesson in the conversation, it was that corporate distress today unfolds in a world that is harder to predict, more exposed to shocks, and far less forgiving of delay. When operating in an environment riddled with uncertainty, supply chains, commodity prices, funding costs, and consumer sentiment are all more vulnerable to sudden disruption.
In that environment, the first mistake is often not ignorance but “hesitation to confront reality early enough,” as Cze Fong puts it, because problems are usually visible internally before they are fully legible in the financial statements.
The practical response is unglamorous but decisive. Companies need a sharper view of their cash flow resilience, their exposure to cost shocks and supply chain disruption, and the discipline of working capital management. Above all, they need to engage lenders early—before covenants are breached, before instalments are missed, and before trust begins to erode.
“Having worked with distressed borrowers across industries and economic cycles, one point remains clear to me: early recognition, open engagement, and timely action usually lead to better outcomes,” she emphasises.
In that sense, rehabilitation and recovery are not opposites so much as adjacent expressions of the same obligation: to preserve value where it can still be preserved, and to accept reality when it cannot. Timing, in these matters, is often the decisive variable.
The views and opinions expressed by interviewees are their own and do not necessarily reflect those of PwC Malaysia. The content and people information presented are accurate as of the time of publication.


Contact us