“Growth is increasingly found in unique places, micro-markets, and specialized sectors.”
“Housing investment opportunities today are increasingly about where shifts are occurring rather than how much activity exists overall.”
Emerging Trends has been tracking the shift toward more localized investment and development strategies for several editions. In 2027, the forces driving that shift—supply constraints, policy fragmentation, AI-driven demand, and infrastructure requirements—have made the geographic calculus more specific and more consequential than ever.
Beyond the multifaceted analysis that has evolved over time for evaluating real estate markets, submarkets, and sites, the 2027 Emerging Trends survey and interviews point to yet another layer of decision points:
Energy and power grid constraints are influencing development decisions for nearly half of respondents (45.3 percent cite it as a top disruptor);
Insurance costs are affecting investment decisions at an even higher rate (72.4 percent cite as moderately or significantly affecting real estate decisions in their markets);
Onshoring and advanced manufacturing, from semiconductor fabrication to defense technology, are creating entirely new demand corridors in markets that did not register on industry radars five years ago; and
Local governance, from permitting timelines to rent regulation to conversion-friendly zoning, increasingly determines whether a market’s growth statistics translate into actionable opportunity.
The time required to move a project from contract to construction varies dramatically by jurisdiction, and that variation changes the risk profile of development by extending the period of exposure to rate changes, cost escalation, and demand shifts. Yet those same barriers to entry may support strong pricing and favorable cap rates for existing assets, a dynamic that separates markets where development is feasible from markets where existing assets carry a scarcity premium. The markets at the top of this year’s rankings share a common thread: each offers an answer to the question facing the industry: why here, and why now?
The overall real estate prospect rankings are derived from the Emerging Trends survey of industry professionals, reflecting a composite of investment, development, and homebuilding prospect scores rated on a one-to-five scale. It is worth noting that scores among the top-ranked markets are closely clustered—small movements in survey responses can meaningfully shift rankings year-over-year—and the rankings should be read as directional indicators of industry sentiment rather than precise ordinals.
This year’s ranking movements reflect a broader shift in how the industry evaluates markets. The largest gains belong to markets with specific, identifiable demand catalysts: San Francisco rises 40 places to fifth (from 45th in 2026), propelled by AI-sector leasing and the technology industry’s continued expansion, which have reduced office vacancy by more than 500 basis points from its peak. Knoxville climbs 46 spots to 20th, anchored by defense-technology activity and affordability. Yet no single metric, new or old, tells the whole story. “No single variable has consistently predicted rent growth since 2000,” cautions a senior executive at a national multifamily housing operator. The ranking shifts illustrate an industry moving toward market-by-market, sector-by-sector, and asset-by-asset evaluation, but those performing that evaluation are the first to acknowledge that the criteria themselves are still evolving.
The housing story in 2027 is as much about affordability as it is about supply and demand. Across the country, the gap between where capital is being deployed and where households can afford to form is widening, and that gap is itself a signal about where the next wave of demand may emerge.
Markets that rank highly for overall real estate prospects do not necessarily rank highly for homebuilding. Entitlement barriers that make existing assets valuable—lengthy predevelopment timelines, restrictive zoning, and limited conversion-friendly policy—make new construction prohibitively slow for builders.
The pattern reverses in markets the industry has largely overlooked. Chicago, Philadelphia, and Detroit are generating housing demand driven by relative affordability, large existing populations, and pent-up household formation, forces that industry sentiment has not yet fully recognized. Affordability is both a social concern and an investment variable. Markets where housing costs consume a smaller share of household income tend to sustain stronger occupancy, lower turnover, and more durable rent growth at the property level, advantages that compound over hold periods. One national multifamily housing operator puts the contrarian case directly: overlooked markets with depressed expectations may outperform precisely because the herd has moved elsewhere.
The divergence between investment and homebuilding sentiment underscores how differently builders and investors evaluate the same markets when affordability, entitlement timelines, and existing supply enter the calculus. A market’s attractiveness depends not just on a single composite score but on which question is being asked: attractive for whom, in which sector, and at what point in the cycle.
Regional Trends
The regional context below provides a framework for how the broader landscape is shifting.
The Southeast: Maturing Beyond Migration
Markets in the Southern and Southeastern regions account for six of the top 10 overall prospect rankings.
But the region’s narrative is evolving from a migration story to one of economic diversification and broader economic maturation. Nashville rises from sixth to second, anchored by a maturing health care sector, alongside a technology campus and a stadium investment that are creating new development corridors. Miami continues to separate itself from the broader Sun Belt through international capital flows and corporate relocation: hedge fund and financial services firms are establishing permanent headquarters, and the metro area’s tourism economy continues to generate substantial economic impact. Raleigh/Durham, ranked fourth, is expanding from its life sciences identity toward a broader manufacturing transformation, with significant statewide manufacturing investment reshaping the Research Triangle.
The caution within the Southeast is familiar but sharpening: in markets where it is easy to build, capital floods in, supply responds, and the resulting oversupply can take years to absorb. Austin, after falling from 15th in 2025 to 30th in 2026, recovers only to 21st when looking ahead to 2027.
The West: Technology as Catalyst
Technology investment, whether in artificial intelligence, semiconductors, aerospace, or data centers, is reshaping physical demand across western markets in ways that extend well beyond the technology sector itself. San Francisco is the most dramatic example, rising from 45th to fifth on the strength of an AI ecosystem that has generated substantial venture capital activity and driven meaningful recovery across office and residential sectors. Investment sales are strong, and trophy assets are trading at levels that signal institutional confidence in the market’s durability.
Phoenix has evolved from an affordability-driven growth story into a leading semiconductor, data center, and advanced manufacturing hub. Orange County blends aerospace and defense with tourism into a diversified growth profile. Seattle, despite a ranking decline (22nd to 38th), has now posted its best new office leasing since 2019 in the first nine months of 2026, with AI-related demand up nine-fold year-over-year, a trajectory that echoes San Francisco’s earlier recovery arc.
The Northeast: Selective Strength
The picture in the Northeast is more nuanced than a single narrative can capture. Manhattan rises from ninth to seventh—continuing its recovery from 42nd in 2022—and the broader New York corridor has three markets in the top 15: Manhattan, Jersey City (eighth), and Northern New Jersey (15th). Manhattan’s recovery is among the most diversified of the profiled markets, with simultaneous strengthening across office, retail, and tourism, and a substantial infrastructure pipeline that reinforces the market’s long-term competitive position.
But the trajectory across the corridor is uneven. The Northeast story is less about uniform strengthening and more about specific demand catalysts—AI and financial services in Manhattan and entitlement-driven scarcity in Jersey City—rewarding certain corridors while broader regional sentiment softens.
The Midwest: The Contrarian Case
Broadly, the Midwest is building a contrarian investment case not on headline growth but on relative value: affordable markets with stable income demographics, constrained supply pipelines, and acquisition bases well below replacement cost. “Utility and entitlement constraints increase the scarcity value of existing assets,” notes a senior executive at a digital infrastructure firm. Markets such as Chicago, Cincinnati, and Indianapolis offer the opportunity to acquire assets at a meaningful discount to what it would cost to build them, a margin of safety that supports durable income returns even without headline rent growth.
In contrast, Columbus, ranked 19th, represents a Midwest market with a growth profile that more closely resembles the Sun Belt, anchored by a roughly 28-billion-dollar semiconductor campus that is creating an advanced manufacturing agglomeration alongside its established logistics strengths. The city ranks third nationally as a data center market and benefits from a university talent pipeline that gives it a competitive advantage in attracting the workforce these industries require.
The South Central: Scale, Infrastructure, and Energy
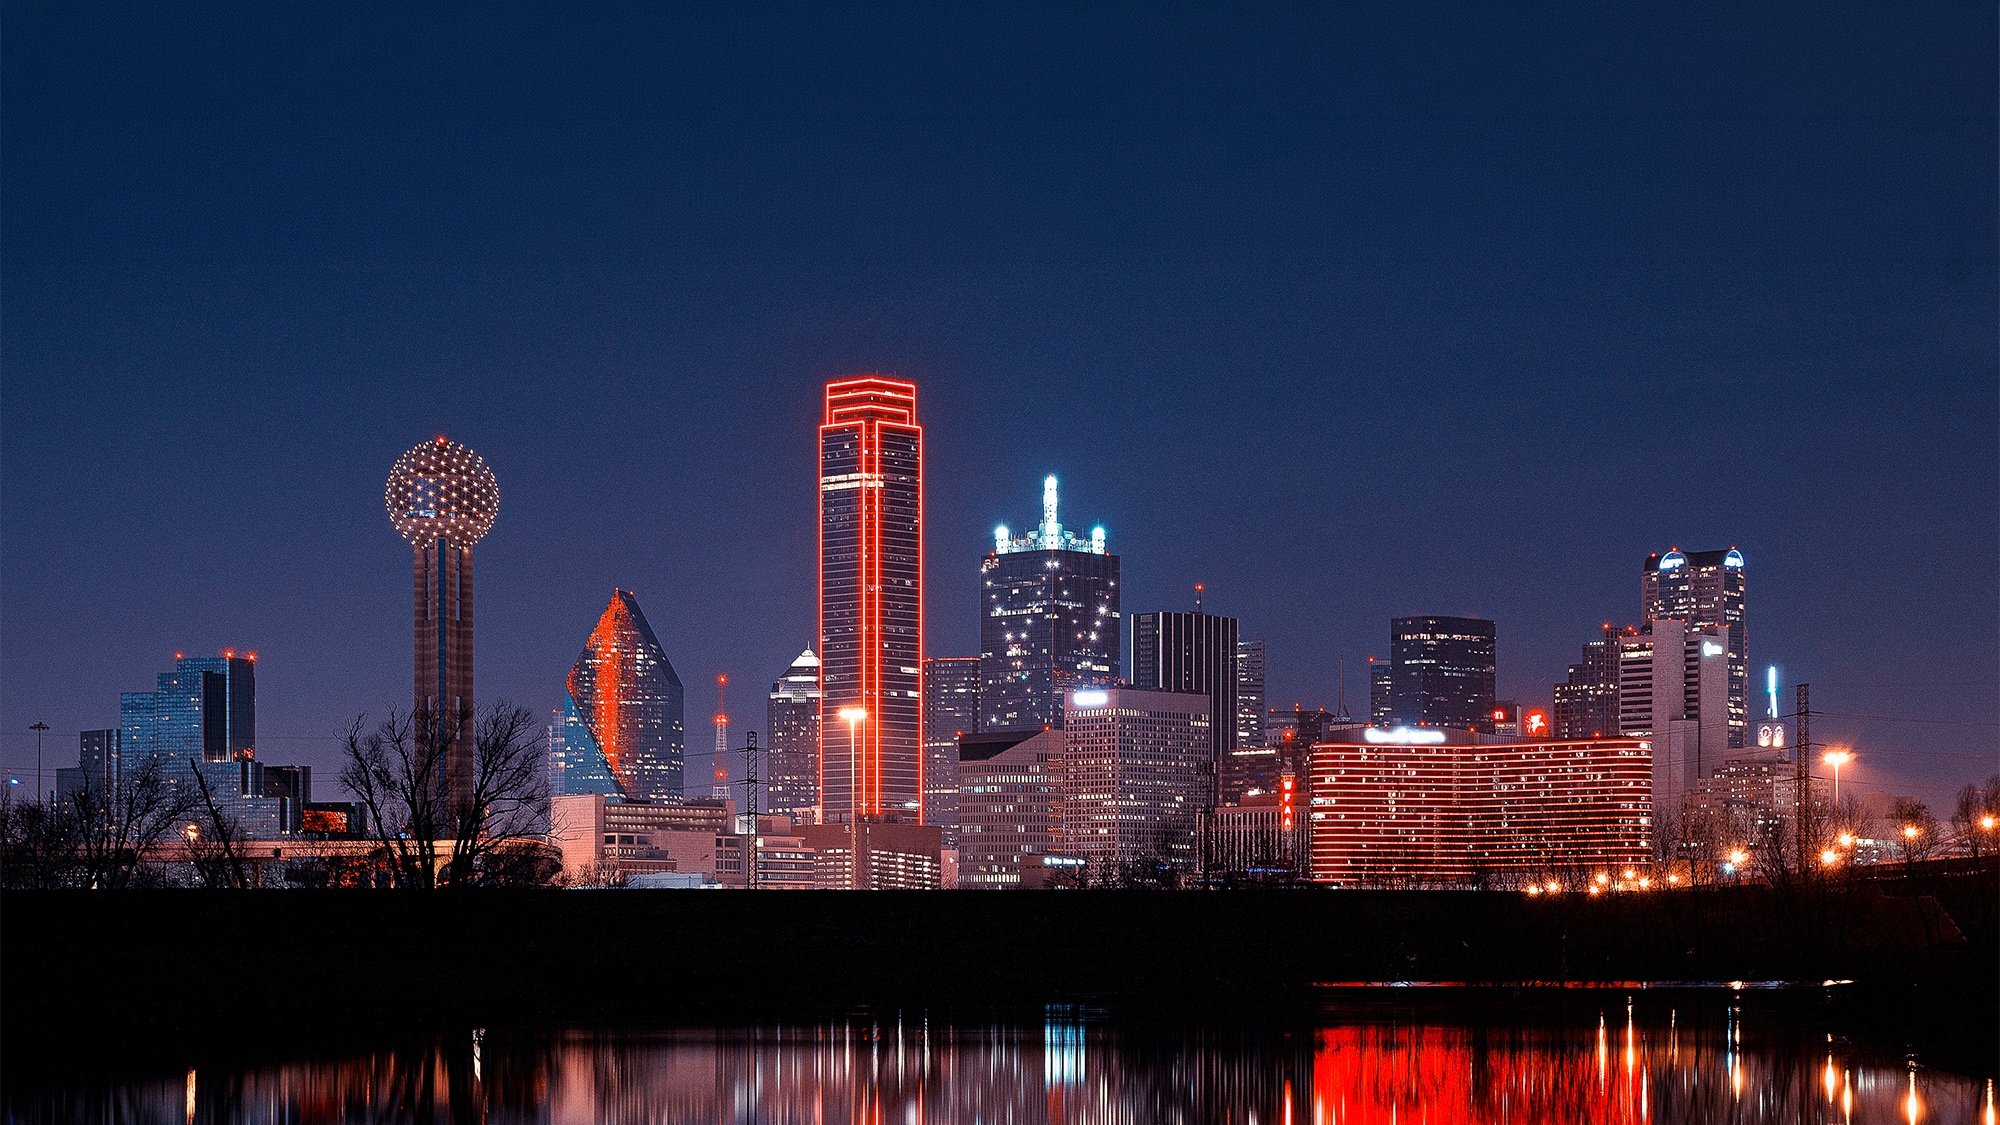
Across the South Central region, the combination of business-friendly governance, available power capacity, and scaled logistics infrastructure is drawing capital to sectors—data centers, advanced manufacturing, and defense—that increasingly define where growth concentrates. Dallas/Ft. Worth retains its position at the top of the overall rankings, a reflection of the market’s scale, diversification, and infrastructure ambitions. The metro area is one of the world’s primary data center markets, has launched the Texas Stock Exchange, and has a multi-billion-dollar projected manufacturing pipeline. Multiple mega-projects are reinforcing the market’s infrastructure in ways that extend its competitive advantages.
Houston continues to benefit from energy-sector strength and an expanding industrial base, ranking among the top markets for warehouse and distribution development as nearshoring activity accelerates along the Texas corridor. The metro area’s port infrastructure, handling the majority of Gulf Coast container traffic, positions it as a primary beneficiary of supply chain reconfiguration. San Antonio is emerging as a defense and cybersecurity hub, leveraging its military installations and lower cost structure than Austin to attract both workforce and investment. And Austin, while contending with the consequences of rapid development, retains the state’s strongest job growth rate and continues to attract technology talent, even as the market works through elevated supply in several sectors.
The Markets
What follows are profiles of the five highest-ranked U.S. markets for overall real estate prospects in 2027—Dallas/Ft. Worth, Nashville, Miami, Raleigh/Durham, and San Francisco—followed by five markets whose individual stories merit close attention—Manhattan, Phoenix, Orange County, Columbus, and Seattle.


