Turn insight into action
We help you solve the problems that matter most so you can act faster and move further.
What would you like to explore?
Analysing the $31 trillion AI build-out
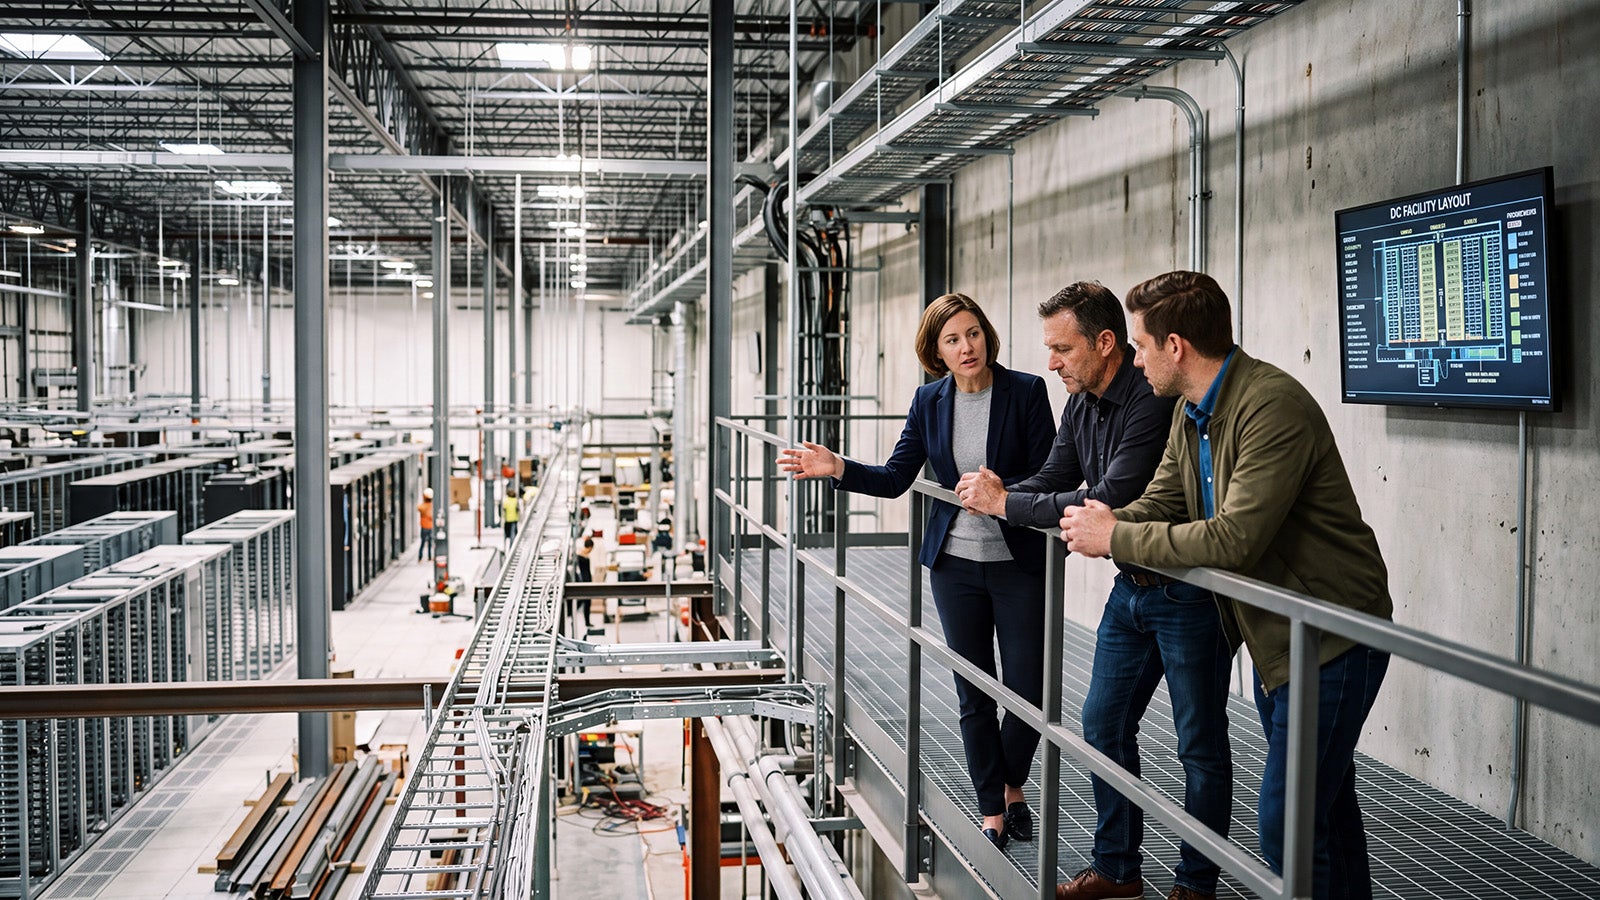
A massive wave of data centre construction will have implications through 2050. Here's how the capital could flow.
The snapshot
The AI infrastructure cycle underway will likely dwarf previous investment booms in areas like railways, electrification, or the internet. The question is where that capital will go. PwC recently commissioned Oxford Economics to model data centre capital expenditure across 46 countries/territories and five regions.
The analysis looked at three scenarios based on the rate of AI adoption. The central scenario projects that data centres attract US$31.6 trillion of capital expenditure globally through 2050. Faster AI adoption pushes capex to about $50 trillion through 2050; a slower adoption path limits the cycle to roughly $20 trillion and leaves stadium-sized data centres around the world sitting half-empty.
Key findings:
- Across all three scenarios, capex rises significantly through 2050. The reason lies in the capital stack of a data centre. The building shell and core site infrastructure—for example, utility connections and fibre routes—may have long, useful lives, but the technology inside doesn’t. Servers, storage systems, networking equipment, GPUs, and other hardware all must be refreshed and upgraded every four to six years.
- Factors such as power availability, data sovereignty requirements, and chip trade flows will determine which regions capture new investment. The Americas account for $16.5 trillion in cumulative capex through 2050, with the US alone responsible for a $15.1 trillion—around 48% of the global total. That’s because the US remains central to the advanced-chip ecosystem and is home to the largest AI model developers, hyperscalers, and AI-native businesses.
- Asia-Pacific accounts for $8.2 trillion in cumulative capex, meaningfully below its share of global GDP. China and India are the largest sources of AI demand, supported by large populations, rapidly expanding digital economies, and substantial headroom for AI to embed in business and consumer activity. Similarly, Europe is punching below its economic weight, for reasons that are familiar and largely self-inflicted: power constraints, planning friction, and fragmented regulation across countries in the region.
For the stakeholders in these regions, the analysis points to several recommendations for how to claim a greater share of the coming wave of capex:
For investors
Underwrite data centres as a hybrid asset. The three layers—property, utilities, and semiconductor exposure—have different durations and risk profiles. Similarly, capital, development, leasing, and counterparty risk flow through the system differently. Treating the asset as a single exposure misses these dimensions.
Diversify away from established hubs. The largest hubs capture the most upside if AI acceleration plays out, but are also the most exposed to slower growth, chip-access constraints, and sovereignty-driven redistribution.
For operators
Compete based on speed to power. Power is the binding constraint under every scenario in this analysis, and the operators that can secure megawatts faster than competitors will capture a disproportionate share of capacity, regardless of which path the market takes.
Design for optionality. Consider phased grid connections, modular capacity, and hardware-flexible cooling. Optionality is itself a hedge against scenario uncertainty. It preserves value if acceleration plays out and limits exposure to stranded capacity if it doesn’t.
For policymakers
Treat data centres as national strategic infrastructure. The most successful jurisdictions coordinate energy, capital, planning, and developer pipelines through a single front door rather than leaving them to parallel private actors.
Plan for a low-carbon build-out from the start. Markets gain a long-term advantage where renewable and firm, low-carbon power capacity scales alongside data centre siting, rather than lagging behind it. The Nordic markets, Chile, and Canada show what that can look like—competitively priced, clean power that becomes a comparative advantage rather than a constraint.
Get in touch
Vinish Bawa
Partner
PwC India
Brian Burns
Partner
PwC United Kingdom
Clara Cutajar
Partner, Global Infrastructure Leader
PwC Australia
