
The growing demand for everyday health
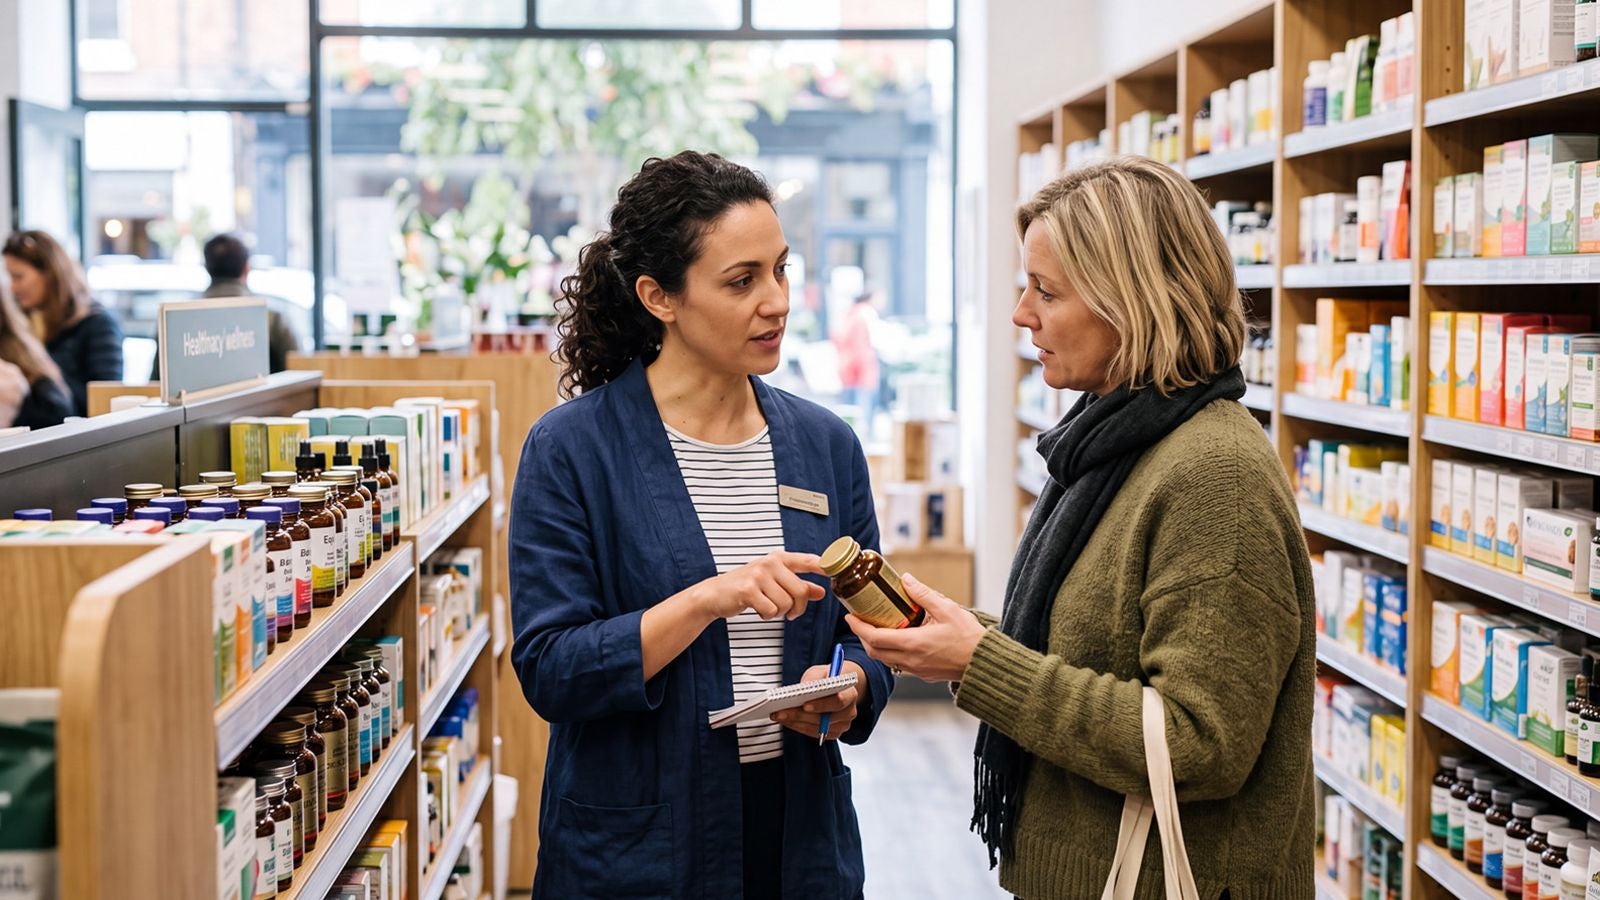
Consumers’ growing focus on health is creating opportunities across consumer goods, retail, and health industries.
Health is no longer confined to the doctor's office or gym. Instead—as PwC’s Voice of the Consumer 2026 survey shows—it's woven into daily routines. The survey drew responses from nearly 22,000 respondents in 27 countries and territories. A key finding: Consumers increasingly seek products and services that offer personalised guidance to help them track factors like nutrition, sleep quality, stress levels, and overall wellness. The goal is not just to avoid disease but to live longer, look better, and feel more confident.
It's a growing opportunity for consumer companies. The global wellness economy reached US$6.8 trillion in 2024—equivalent to roughly one in every eight consumer dollars spent. The Global Wellness Institute projects the number will grow to $9.8 trillion by 2029.
Those dollars are spent on yoga mats, athleisure wear, vitamins, and increasingly on services wrapped around products: a ring that tracks sleep, an app that coaches exercise, or a watch that monitors heart rate and blood pressure. PwC’s research finds that 63% of respondents have a clear interest in health insights and diagnostics, and 60% in coaching, programmes, and behaviour change.
But services are only one part of the equation. Our survey shows that consumers still prioritise value for money, affordability, ease of use, and clear information. For companies, the opportunity lies in making health easier to understand, choose, and act on.
Here's how companies can capitalise:
Food and beverage companies. Develop new products designed around occasions such as morning and midday energy dips, recovery, and sleep, with products designed for specific goals such as satiety, mood, longevity, and metabolic support. Look beyond individual transactions to offer guidance, prompts, or subscriptions that help consumers understand what to consume when, and how a product supports specific health goals.
Household and personal care. Consumers want products at the intersection of health, design, beauty, and self-confidence. Companies can view the home, bathroom cabinet, and bedroom as health environments, with offerings that support sleep, recovery, prevention, and daily wellbeing. Use diagnostics and AI analysis of skin and scalp, or sleep environment data to give consumers clear, practical recommendations without adding cost or complexity.
Omnichannel retail. Retailers already benefit from frequent customer interactions and data. The limiting factor is permission. Consumers are selective about who they trust with health data. Because of that, retailers should build trust using pharmacy relationships and offer expert guidance and clear value before asking consumers to share more . They can also organise health in terms of goals rather than categories, connecting food, supplements, devices, diagnostics, pharmacy advice, and services to needs related to sleep, stress, weight, and energy.
Pharmaceutical. As consumers take a more active role in how they manage health, pharma companies will need stronger capabilities in patient engagement, digital support, behavioural coaching, data partnerships, and real-world evidence. To accomplish this, they can build partnerships involving providers, pharmacies, diagnostics, digital health, data platforms, and consumer health players to help people manage the broader behaviours that lead to better health outcomes.
Get in touch
Anthony Bruce
Global Health Industries Leader
PwC United Kingdom
Sabine Durand-Hayes
Global Consumer Markets Leader
PwC France
Harald Dutzler
Global Consumer Goods Leader, Partner
Strategy& Austria
